Evaluating Competitive Market Share Distribution Across Global Computational Fluid Dynamic Industry Software Sectors
Understanding Competitive Concentration Among Industry Leaders
The global software ecosystem is characterized by a moderately concentrated enterprise tier where a select group of multinational technology corporations commands a dominant share of total revenue. The Computational Fluid Dynamic Cfd Software And Service Market Share highlights how leading software vendors maintain their competitive advantage through comprehensive product suites, robust solver accuracy, and extensive global support networks. These industry giants continuously acquire specialized technology startups to integrate niche capabilities—such as electrochemistry modeling, particle tracking, and advanced mesh generation—into their flagship platforms. While enterprise-grade software suites dominate large corporate accounts, open-source simulation tools and specialized boutique vendors capture significant traction among academic institutions and agile startups seeking cost-effective alternatives. This competitive interplay fosters continuous technological innovation, pushing vendors to refine their user interfaces, enhance solver performance, and expand interoperability with broader computer-aided engineering ecosystems.
Strategic Importance of Professional Consulting Services
Beyond software license sales, professional engineering services represent a vital revenue pillar and strategic differentiator within the global market ecosystem. Many industrial enterprises lack specialized internal fluid dynamics expertise or struggle with bandwidth constraints during peak product development cycles, prompting them to outsource complex simulation projects. Specialized engineering service firms provide expert consulting, custom model validation, workflow automation, and advanced training to help clients maximize their software return on investment. Furthermore, services play a critical role in bridging the gap between theoretical software output and practical manufacturing realities. Vendors and independent consultancies that offer comprehensive technical support and tailored engineering services secure deeper client loyalty, higher customer retention rates, and lucrative multi-year service contracts across demanding industrial sectors.
Differentiation Through Specialized Industry Solutions
To capture expanding market segments, software vendors increasingly develop tailored vertical solutions optimized for specific industrial applications rather than relying solely on generic general-purpose solvers. Specialized software modules designed for electronics cooling, turbomachinery design, marine hydrodynamics, and biomedical blood flow analysis enable engineers to work within industry-specific workflows and terminology. These targeted solutions reduce setup time, incorporate domain-specific physics models, and ensure compliance with relevant industrial standards. By addressing the unique challenges of niche engineering fields, software providers attract specialized enterprise clients who demand extreme precision and validated accuracy within their respective domains, driving high-margin revenue growth and reinforcing competitive market positioning.
Ecosystem Alliances and Collaborative Technology Partnerships
Strategic partnerships and technology integrations are vital mechanisms through which software vendors expand their market reach and enhance product value propositions. Collaboration between simulation software developers, computer-aided design manufacturers, and cloud infrastructure providers creates seamless, end-to-end engineering workflows. For instance, tight integration between CAD geometry tools and CFD meshing algorithms allows design engineers to evaluate fluid behavior directly within their familiar modeling environment without cumbersome data file export steps. Additionally, alliances with hardware manufacturers ensure that solvers are optimized for the latest multi-core central processing units and graphics processing unit accelerators. These collaborative ecosystems reduce integration friction for end users and establish powerful network effects that solidify market leadership.
Future Outlook for Market Share Dynamics
As the industry matures, competitive positioning will increasingly depend on a vendor's ability to embrace cloud-native deployment, artificial intelligence automation, and open-source interoperability. While established enterprise software vendors hold significant advantages in brand recognition and legacy customer relationships, agile challengers leveraging modern cloud architectures and AI-driven workflows are gaining notable momentum. Companies that successfully balance robust solver validation with intuitive user accessibility will capture expanding market share, shaping the future trajectory of engineering simulation software worldwide.
➤ Explore Our Latest Trending Reports!
Categorii
Citeste mai mult
Evaluating the financial structure, capital investments, and institutional equity allocations surrounding the consumer lending domain reveals a stable Retail Lending Market Value recognized across global public equity markets and private debt portfolios. Consumer credit assets have evolved into essential financial instruments that generate steady net interest income for banking institutions...

The Glycomics Market research report lays emphasis on primary as well as secondary drivers, leading market segments, market share, regional analysis, and possible sales volume. It gives a detailed explanation on what the market definition, applications, classifications, market trends, and engagements are for a healthcare industry. Further, it delves into a comprehensive market overview with...
What regulations govern the disposal of expired medical components from a Roadside Car First Aid Kit Manufacturer? This question rarely reaches purchasing departments. Most buyers assume expired kits go into regular trash. This assumption violates laws across multiple jurisdictions. Expired antiseptic wipes contain chemical preservatives. Outdated bandages may harbor bacterial growth. Unused...
Finding elegant ethnic fashion has never been easier with Pakistani Suits Online UK from Rang Jah. Designed for women who appreciate timeless craftsmanship and modern style, our exclusive collections bring authentic Pakistani fashion directly to your doorstep across the UK. Whether you're updating your wardrobe for a special occasion or searching for everyday elegance, Rang Jah offers...
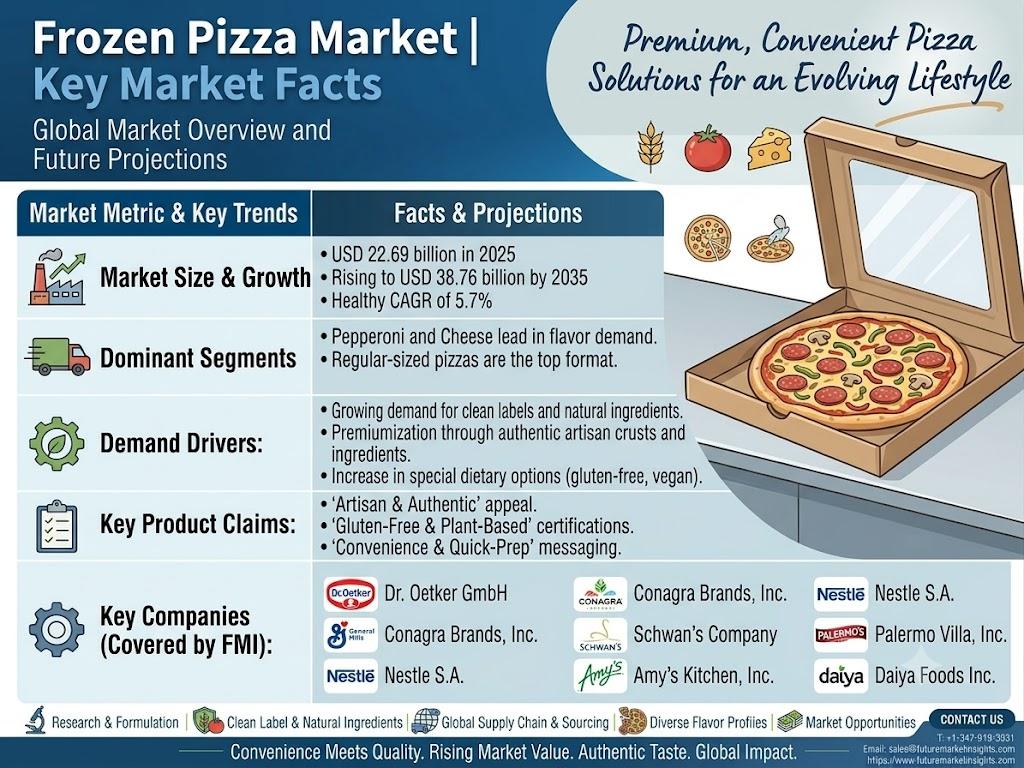
NEWARK, Del., October 16, 2026 — The global Frozen Pizza Market is gaining momentum as consumers increasingly prioritize convenient meal preparation, extended shelf life, product variety, and restaurant-style eating experiences at home. According to the latest market intelligence report published by Future Market Insights (FMI), the market is projected to increase from USD 22.69 billion...