


Directors and Officers Insurance Market Demand Fueled by Regulatory Compliance Requirements
As digital infrastructure becomes the backbone of global commerce, corporate boards face heightened legal scrutiny over their organization's cybersecurity posture and data governance protocols. Regulatory authorities and institutional investors no longer view cyber incidents solely as IT operational failures; instead, they are increasingly framed as systemic failures of executive oversight. When major data breaches or ransomware events occur, shareholders frequently file derivative lawsuits alleging that directors breached their fiduciary duty of care by failing to implement robust cybersecurity controls. Comprehensive data from the Directors And Officers Insurance Market Forecast emphasizes the necessity for corporate leadership to maintain active risk oversight, engage in routine crisis response planning, and ensure enterprise-wide compliance with international data privacy laws.
The underwriting landscape for executive coverage has adapted swiftly to these digital threats. Underwriters now evaluate an organization's cyber resilience, incident response readiness, and board-level technology expertise before finalizing policy terms. If a cyber incident leads to plummeting stock valuations or costly regulatory investigations, executive liability policies are called upon to absorb massive legal defense bills and potential settlement costs. Consequently, organizations must ensure clear alignment between their dedicated cyber insurance policies and executive coverage structures, eliminating potential coverage gaps or disputes regarding policy priority when parallel litigation arises.
Frequently Asked Questions
Can directors and officers be sued individually following a corporate data breach?
Yes, shareholders or regulatory bodies can sue executives individually, alleging inadequate oversight, failure to implement reasonable security controls, or misrepresentation of the company's cybersecurity readiness.
How does a dedicated Cyber policy interact with executive liability coverage during a major breach?
Cyber insurance typically covers direct first-party losses and third-party liabilities, while executive liability steps in if shareholders or regulators sue the board members personally for breach of fiduciary duty related to the incident.
➤➤➤Explore MRFR’s Related Ongoing Coverage In Semiconductor Industry:
Cybersecurity Insurance Market
Debt Collection Software Market
Categorias
Leia Mais
Modern electrical enclosures need more than simple sealing to perform reliably in outdoor and industrial environments. A Waterproof Breathable Valve Manufacturer can provide ventilation components that balance enclosure protection with controlled air exchange, while choosing the right Waterproof Breathable Valve Manufacturer can help equipment producers address pressure changes, condensation,...
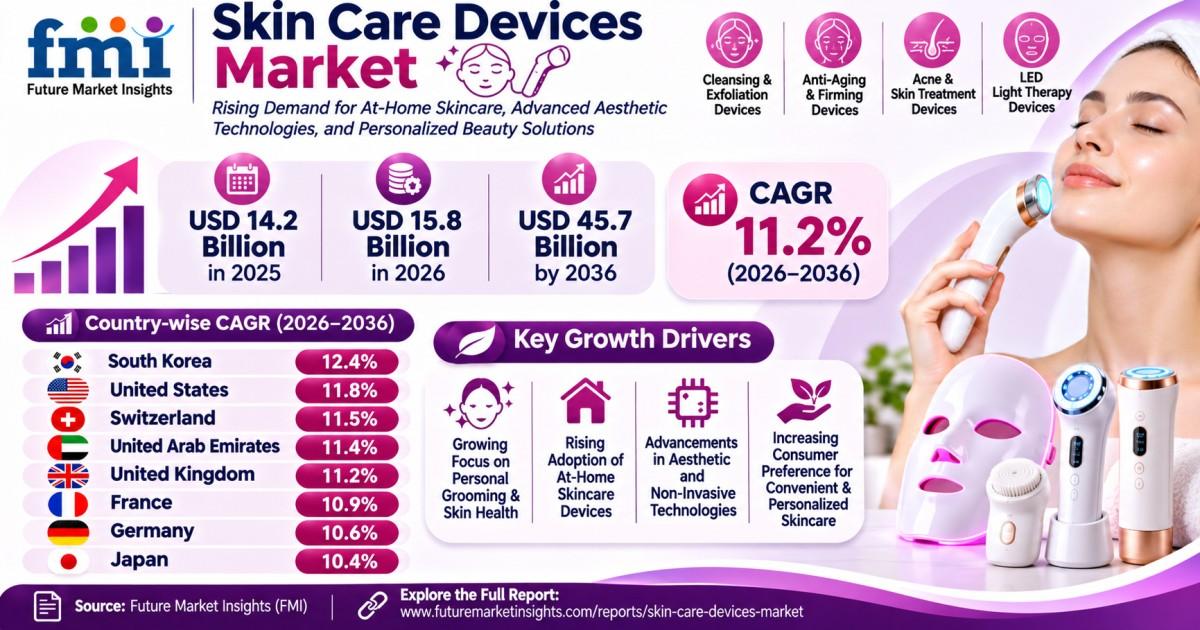
The skincare industry is moving beyond traditional creams, serums, and salon-based facials as consumers increasingly explore technology-driven solutions for healthier-looking skin. From LED light therapy masks and microcurrent devices to radiofrequency treatments and advanced laser systems, skin care devices are becoming an important part of both professional beauty services and everyday...
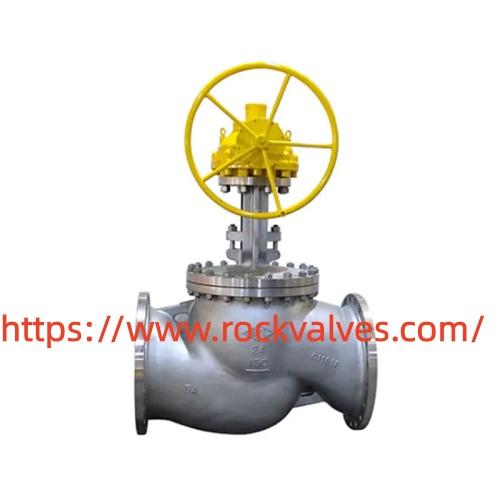
Cryogenic Gate Valve for Low Temperature Service requires careful consideration before purchase because industrial projects depend on stable flow control and reliable construction. Buyers need to review materials, manufacturing processes, connection methods, and application needs before selecting a product. Every project has different operating conditions, so a detailed evaluation helps avoid...
The commitment to pure, unadulterated food is steering a growing number of shoppers toward the Organic fruit chips market. Organic certification guarantees that the fruits are grown without synthetic pesticides, herbicides, or genetically modified organisms, a promise that resonates deeply with clean eating enthusiasts. As per Market Research Future, the organic fruit chips segment is...

Work environments such as storage tanks, pipelines, underground chambers, sewers, tunnels, and industrial vessels can contain dangerous atmospheric conditions. Workers entering these confined spaces may face exposure to toxic gases, combustible substances, or insufficient oxygen. Since these hazards are not always visible or detectable through smell, reliable monitoring equipment is essential....