Combustion Ion Chromatography System Market Forecast to Reach USD 1.2 Billion by 2035
High-throughput water analysis has become the operational pressure point for laboratories tasked with monitoring drinking water, wastewater, and industrial discharge under tightening regulatory schedules. According to WiseGuy Reports, the global Combustion Ion Chromatography System Market was valued at USD 744.1 million in 2024, rose to USD 776.9 million in 2025, and is projected to reach USD 1,200 million by 2035, expanding at a compound annual growth rate of 4.4% across the 2026–2035 forecast period. That rate is characteristic of analytical capital equipment, where growth tracks testing obligations and laboratory budgets rather than consumer demand. The high-throughput water analysis requirement is therefore the correct analytical lens, because it explains why instrument vendors are competing on sample throughput and workflow automation rather than on separation chemistry alone.
Report Key Statistics
The report establishes a clear quantitative baseline. Market value moves from USD 744.1 million in 2024 to USD 776.9 million in 2025, en route to USD 1,200 million by 2035—approximately USD 456 million in additional value creation over the forecast horizon.
By application, environmental testing leads as the highest-valued sector, valued at USD 200 million in 2024 and projected to reach USD 320 million by 2035, driven by increasing regulations and the need for environmental monitoring. Pharmaceutical analysis was valued at USD 170 million in 2024 and is projected to reach USD 270 million by 2035. Food and beverage testing was valued at USD 150 million in 2024 and is projected to reach USD 240 million by 2035. Water quality testing is expected to reach USD 160 million by 2035, chemical manufacturing is projected to reach USD 210 million by 2035, and water quality testing shows gradual increases as safeguarding water resources becomes a central concern globally.
Regionally, North America leads, valued at USD 250 million in 2024 and projected to reach USD 400 million by 2035, benefiting from advanced technologies and robust research and development initiatives. Europe exhibits stable growth driven by increasing industrial applications and rigorous environmental regulations. Asia-Pacific is experiencing strong growth, increasing from USD 180 million in 2024 to USD 290 million by 2035, supported by expanding industrial sectors and growing emphasis on quality control. South America reflects moderate increase fueled by rising infrastructure investment, while the Middle East and Africa experiences gradual expansion.
By type, single column systems have established a reputation for efficiency and effectiveness in ion separation leading to a strong growth trajectory, multi-column systems demonstrate steady expansion through ability to handle complex sample matrices, and modular systems attract interest through flexibility and scalability in various laboratory environments.
By component, detectors hold a significant position due to their crucial role in ensuring high accuracy and sensitivity, ion chromatography columns exhibit strong growth driven by advances in material technology and separation efficiency, sample vials expand steadily correlating with demand for precise sample preservation, pumps increase moderately as innovations produce more efficient models, and software components gain traction reflecting a shift toward integrated solutions that improve operational efficiency.
By end use, pharmaceuticals has emerged as a significant contributor driven by stringent quality control measures and increasing R&D spending, food and beverage exhibits steady expansion due to rising consumer awareness about food safety, environmental agencies play a crucial role in analyzing pollutants and ensuring compliance, academic research shows a gradual uptick in demand for advanced analytical techniques, and the chemical industry maintains a stable presence.
The report profiles key companies including Hitachi HighTechnologies, Analytik Jena, Metrohm, Malvern Panalytical, Buck Scientific, Hach, Thermo Fisher Scientific, Waters Corporation, Elitech Group, PerkinElmer, Dionex, JASCO, GE Analytical Sciences, Agilent Technologies, and Skalar Analytical.
Industry Trends Reshaping the Category
Regulatory Obligation as Demand Anchor
The report identifies growing demand for environmental testing as a key market dynamic, noting governments worldwide are implementing stricter environmental laws aimed at reducing pollution, which has heightened the need for effective testing and analysis of water and air samples. It cites the Clean Air Act in North America as incentivizing adoption of emission testing technologies, and the European Green Deal in Europe as driving need for accurate emissions monitoring solutions.
The analytical point is that instruments specified for regulatory compliance have unusually durable demand: once a testing method is written into regulation, laboratories must maintain the capability to perform it, which creates replacement and expansion demand independent of economic conditions.
Throughput Pressure on Water Utilities
The report notes water quality testing remains essential, showing gradual increases as safeguarding water resources becomes a central concern globally, with substantial investments in water quality assurance and monitoring highlighting its importance in public health and environmental sustainability. Recent developments documented in the report illustrate the throughput response: Thermo Fisher Scientific launched in June 2025 a new high-throughput combustion ion chromatography system designed for fast multi-sample testing in water utilities.
This is analytically decisive because utilities must test large sample volumes against fixed reporting deadlines, so per-sample time and labour requirements determine whether a laboratory can meet obligations with existing staff. Throughput is therefore a purchasing criterion, not merely a convenience feature.
Workflow Integration and Partnership
The report observes that technological advancements in automation and integration with data analytics are enhancing functionality and efficiency, attracting end-users seeking to streamline operations. Recent developments show vendors organizing around integrated workflows: Waters Corporation announced in March 2025 a strategic partnership with Skalar Analytical to co-develop integrated combustion ion chromatography workflows for environmental and drinking-water analysis. Metrohm completed the acquisition of Buck Scientific's IC division in April 2024 to expand its global combustion IC system portfolio.
Taken together, these moves indicate that competition is shifting toward complete workflow solutions—instrument plus method plus software—rather than individual hardware. This raises the integration bar for smaller suppliers, which explains both the partnership and the acquisition.
Automation Replacing Manual Preparation
The report notes the rise of automated systems and integration of data analysis software creates opportunity for manufacturers to build more efficient and user-friendly instruments, and observes an increased focus on user training and support services to ensure optimal use of systems. The analytical implication is that sample preparation—historically the labour-intensive and error-prone stage—is where automation delivers the greatest throughput gain, which is why software capability is gaining traction as a component segment.
Challenges Constraining Growth
The report identifies several constraints. The market's 4.4% growth rate reflects dependence on laboratory capital budgets and long instrument replacement cycles, which limit annual growth regardless of expanding testing requirements.
Technical complexity is a further barrier. The report notes multi-column systems are required for complex sample matrices, indicating simpler single-column configurations cannot serve all applications, which raises the entry price for laboratories needing broad capability. Skilled operator requirements compound this, since capability without trained staff does not translate into usable analytical output—hence the report's emphasis on training and support services.
Cost constraints are also material. The report notes cost-effectiveness alongside reliability and after-sales support as customer concerns, indicating price sensitivity persists even among regulated buyers. Finally, the Middle East and Africa region experiences gradual expansion rather than growth, reflecting that adoption depends on laboratory infrastructure and enforcement capacity—factors that develop slowly.
Future Outlook and Expert Discussion
The report's outlook identifies technological advancements in chromatography, increasing demand in environmental analysis, rising need for quality control, expansion in pharmaceutical applications, and growth in food safety testing as key opportunities. It recommends investing in advanced sensor technologies to enhance precision and efficiency, expanding partnerships with research institutions and universities to drive innovation, and leveraging data analytics and machine learning to optimize system performance and predictive maintenance.
The report notes a 20% increase in patent filings related to new chromatography technologies in the last five years, indicating robust interest in advancing this analytical domain.
The report's competitive analysis offers a useful contrast between two leading players. Hitachi HighTechnologies has established a significant presence by leveraging advanced technology and strong R&D capabilities, excelling in creating high-performance chromatography systems renowned for sensitivity, accuracy, and reliability. It invests in next-generation systems incorporating state-of-the-art detection techniques, supported by an extensive customer support network and comprehensive training services enhancing client satisfaction and retention.
Analytik Jena is renowned for dedication to high-quality analytical instruments, focusing on producing versatile ion chromatography systems catering to environmental monitoring, food safety, and pharmaceuticals. It is recognized for user-friendly designs and ability to provide reliable data output crucial for compliance with strict regulatory standards, with emphasis on sustainability and eco-friendly solutions resonating with current market trends.
The analytical distinction is that Hitachi HighTechnologies emphasizes advanced detection methods and superior R&D, positioning itself at the forefront of innovation with premium performance, while Analytik Jena offers a broader spectrum of versatile solutions with strong focus on usability and environmental considerations. Both are viable because the market segments by buyer priority: research-intensive laboratories weigh detection capability, while routine compliance laboratories weigh ease of use and cost of ownership.
Conclusion
High-throughput water analysis currently drives the market's growth trajectory, anchored by environmental regulation and utility reporting obligations, and constrained by long instrument replacement cycles. Emerging opportunities lie in automation that reduces per-sample labour, workflow partnerships bundling instruments with validated methods, modular configurations for smaller laboratories, and expansion in Asia-Pacific where industrialization is increasing testing demand. Technological developments in detection sensitivity and integrated software are raising analytical capability while lowering the skill threshold required to operate systems, which matters because trained-staff shortages limit throughput as much as instrument speed does.
Over the long term, the direction is toward analytical workflows purchased as complete compliance solutions rather than as individual instruments, with software providing the audit trail regulators require. This will favour vendors able to supply integrated systems and disadvantage component-only suppliers. As the Combustion Ion Chromatography System Market advances toward its 2035 valuation, manufacturers that pair throughput capability with defensible documentation and service support will capture the most durable share, because in regulated water testing the value of an instrument rests on the credibility of the results it produces under deadline pressure.
Categorii
Citeste mai mult
Shower Tray Support Legs can help installers create a stable foundation for a bathroom tray while allowing adjustments to suit the actual conditions of the installation site. Bathroom renovation projects often involve uneven surfaces, limited working space, drainage connections, and existing structural conditions. Careful component selection and correct installation can help project teams...
The Gas to Liquid Market Share landscape reveals a dynamic and competitive industry, with established energy majors and innovative technology providers vying for position in this high-growth sector. This analysis provides a comprehensive breakdown of market share by product, application, region, and key players, offering valuable insights for investors and stakeholders. By product, GTL Diesel...
Industry analysis highlights that the Anti Lock Braking System Electronic Stability Control System Market Share is characterized by a fragmented competitive structure with a very high level of competition. Leading companies include Bosch, Continental AG, Denso Corporation, ZF Friedrichshafen AG, Hyundai Mobis, and several others. Investments in research and development remain the most...
The performance of an Electroplated Diamond Hole Saw is strongly determined by its manufacturing process. Unlike mechanically sharpened cutting tools, this type of hole saw relies on electrochemical bonding technology that embeds diamond particles directly onto a steel substrate. The precision of this process directly affects cutting stability, lifespan, and hole accuracy. Core...

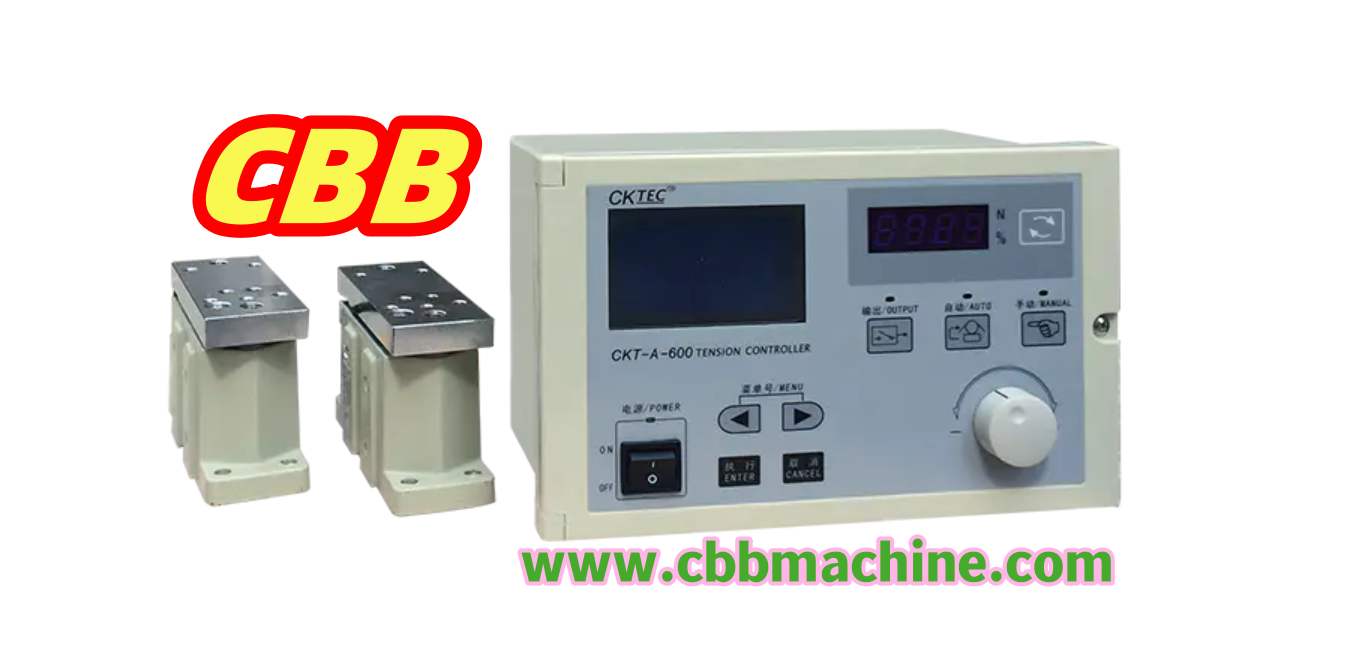
In modern converting and winding environments, material stability often determines how smoothly a production line operates from beginning to end. Tension Controller from Cbbmachine is designed to assist with balanced web handling during unwinding, rewinding, coating, and laminating procedures. Its role within industrial systems reflects the increasing demand for controlled material movement and...