The Well Logging Tools Industry: Sensor Physics, Tool Survivability, and the Interpretation Shift
A well logging tool is a measurement instrument designed to survive an environment that destroys most electronics. It descends two to eight kilometres into a borehole, at pressures exceeding a thousand atmospheres, temperatures above the boiling point of water, in drilling fluid that abrades and corrodes. The Well Logging Tools Industry is therefore organized around survivability engineering as much as measurement physics. This analysis maps the industry's structure and identifies where competitive advantage accumulates.
The Industry Value Chain
The sector operates across five interconnected layers.
Sensor and detector components. Electrodes, scintillation crystals, photomultiplier tubes, acoustic transducers, and pressure gauges. Each measurement physics requires a different detector—and detector quality determines data quality.
Tool housing and pressure containment. High-strength alloys, seals, and pressure bulkheads. A housing failure floods the electronics and loses the run.
Electronics and telemetry. Downhole processing, data storage, and transmission. Wireline telemetry transmits in real time; logging-while-drilling tools use mud-pulse or electromagnetic telemetry with bandwidth constraints that force downhole processing.
Conveyance systems. Wireline cable, slickline, coiled tubing, and drill-string integration. Conveyance determines which wells a tool can reach—and horizontal wells require push capability that gravity-based wireline cannot provide.
Interpretation and analytics. Petrophysical processing, machine learning models, and integrated software platforms. This layer is where the industry's value migration is most pronounced.
The market is populated by a range of players from established multinationals to emerging regional firms. Schlumberger, Halliburton, Baker Hughes, Weatherford International, National Oilwell Varco, GE Oil & Gas, Petrobras, Kuwait Oil Company, and China National Petroleum Corporation form the competitive tier.
Tool Survivability as the Governing Metric
No factor shapes industry economics more than whether a tool survives its run.
A wireline tool that fails downhole requires a fishing operation or a trip—both measured in rig time. A logging-while-drilling tool failure is worse: it may require pulling the entire drill string.
Three engineering consequences follow:
Temperature ratings determine addressable wells. Tools rated for higher temperatures can log deeper, hotter formations. As wells go deeper, temperature rating becomes a specification gatekeeper.
Vibration tolerance determines LWD viability. Tools integrated into the drill string experience shock and vibration that wireline tools avoid. Shock mounting, component selection, and ruggedisation determine whether LWD tools complete their runs.
Redundancy determines system availability. Critical sensors are duplicated, and downhole processing identifies failures before data is lost.
The Interpretation Shift
The industry's defining commercial shift is from measurement supply to interpretation supply.
The integration of digital technologies such as artificial intelligence and machine learning appears to enhance accuracy and efficiency—leading to improved decision-making for operators, optimising production and reducing costs.
The practical consequence is that a logging run generates far more data than traditional interpretation can process efficiently. Machine learning models trained on large well databases can identify patterns, flag anomalies, and produce preliminary interpretations faster than manual review.
Recent industry activity confirms the direction: Halliburton integrated artificial intelligence into its well logging processes, providing clients with better analytical tools. Schlumberger continues to innovate with new digital well services. CGG's advancements in geophysical solutions have fostered collaborations in data analysis.
The industrial logic is that tool hardware is converging in capability while interpretation software is differentiating. Suppliers with analytics platforms capture the decision layer—and the customer relationship that comes with it.
The Adjacent Market Expansion
The industry's second structural force is application diversification.
Oil and gas exploration remains dominant, projected to reach approximately USD 5.0 billion by 2035. But environmental monitoring is the fastest-growing application, driven by regulation and sustainability awareness—logging tools gather insight into ground conditions and assess impacts of various activities.
Geothermal energy is projected to reach approximately USD 1.5 billion by 2035. The technical requirements overlap substantially with oilfield logging: high-temperature tools, fracture characterisation, and reservoir assessment. Water resource management applies logging to aquifer characterisation.
The strategic significance is that the toolset transfers. A supplier with high-temperature sensor capability and interpretation software can serve geothermal and environmental markets with modest adaptation—diversifying revenue away from oil price cycles.
Technology and Conveyance Dynamics
Wireline logging holds the largest share, projected to reach approximately USD 3.84 billion by 2035. Its reliability and comprehensive data collection capability have made it the cornerstone of well logging—allowing operators to make informed decisions based on accurate wellbore information.
Logging while drilling grows fastest, projected to reach approximately USD 3.68 billion by 2035. It is emerging as a preferred alternative due to advancements that streamline operations and minimise downtime, supporting real-time data acquisition during drilling.
Slickline logging serves lighter intervention applications.
The technology mix matters commercially: wireline tools are less capital-intensive and simpler to develop, while LWD tools require ruggedisation and downhole processing capability—raising barriers to entry.
Tool Type Structure
Electrical logging tools are the backbone, offering reliable data through resistivity and conductivity measurements. Their versatility and compatibility across logging environments make them the preferred choice—projected to reach approximately USD 3.5 billion by 2035.
Nuclear logging tools emerge rapidly, driven by advancements enhancing accuracy in subsurface imaging—projected to reach approximately USD 2.0 billion by 2035.
Acoustic logging tools provide mechanical property assessment relevant to completion design.
Pressure logging tools confirm reservoir connectivity and fluid gradients.
Demand-Side Structural Change
Industry demand is being reshaped by forces outside the logging sector.
Rising energy demand — the IEA forecasts substantial growth by 2040, necessitating efficient exploration methods.
Increased exploration investment — exploration budgets are rising, reflecting renewed focus on discovering reserves.
Regulatory compliance — stringent standards require accurate data collection and environmental protection.
Sustainability focus — the energy sector faces pressure to minimise ecological footprint, driving non-invasive techniques.
Unconventional reservoir development — complex geological formations require sophisticated logging tools.
Regional Industry Structure
North America holds approximately 45% of global share, driven by demand for advanced drilling technologies and regulatory support. Schlumberger, Halliburton, and Baker Hughes anchor the competitive landscape, with the United States leading and Canada contributing through oil sands and shale.
Europe holds approximately 25% share, driven by enhanced oil recovery and renewable transition. Norway and the UK lead, with carbon-reduction regulation acting as catalyst.
Asia-Pacific holds approximately 20% share and grows fastest, driven by exploration in China and India plus government initiatives to boost domestic production. China National Petroleum Corporation is prominent.
Middle East and Africa holds approximately 10% share, driven by demand for efficient extraction. Saudi Arabia leads, followed by the UAE and Nigeria.
Strategic Priorities for Industry Participants
Four priorities separate competitive positioning from commoditization:
-
High-temperature and high-pressure tool capability — specification gatekeeper as wells deepen
-
AI-driven interpretation platforms — capturing the decision layer
-
Logging-while-drilling ruggedisation — the fastest-growing technology segment
-
Adjacent market transfer — geothermal, environmental, and water resource diversification
Conclusion
The well logging tools industry is shaped by sensor survivability and interpretation capability. Growth through 2035 will accrue to suppliers who extend tool temperature and pressure ratings, deliver AI-driven interpretation, ruggedise LWD capability, and transfer their toolset into adjacent markets. The instrument still descends the borehole—but the industry's competitive logic is increasingly about what happens to the data once it returns.
Europe Offshore Wind Installations Market
Middle East & Africa Fuel Cell Market
Middle East & Africa Floating LNG Power Vessel Market
Europe Offshore Floating Solar Panel Market
Upstream Oil & Gas Analytics Market
Alternative Solar Photovoltaic Technology Market
Catégories
Lire la suite
Carbide Rotary Burs should be evaluated according to the actual requirements of the machining project. Buyers need to consider the workpiece material, tool geometry, dimensions, shank compatibility, equipment, working area, and expected application before confirming an order. A structured purchasing process can make it easier to compare specifications and communicate requirements with a...
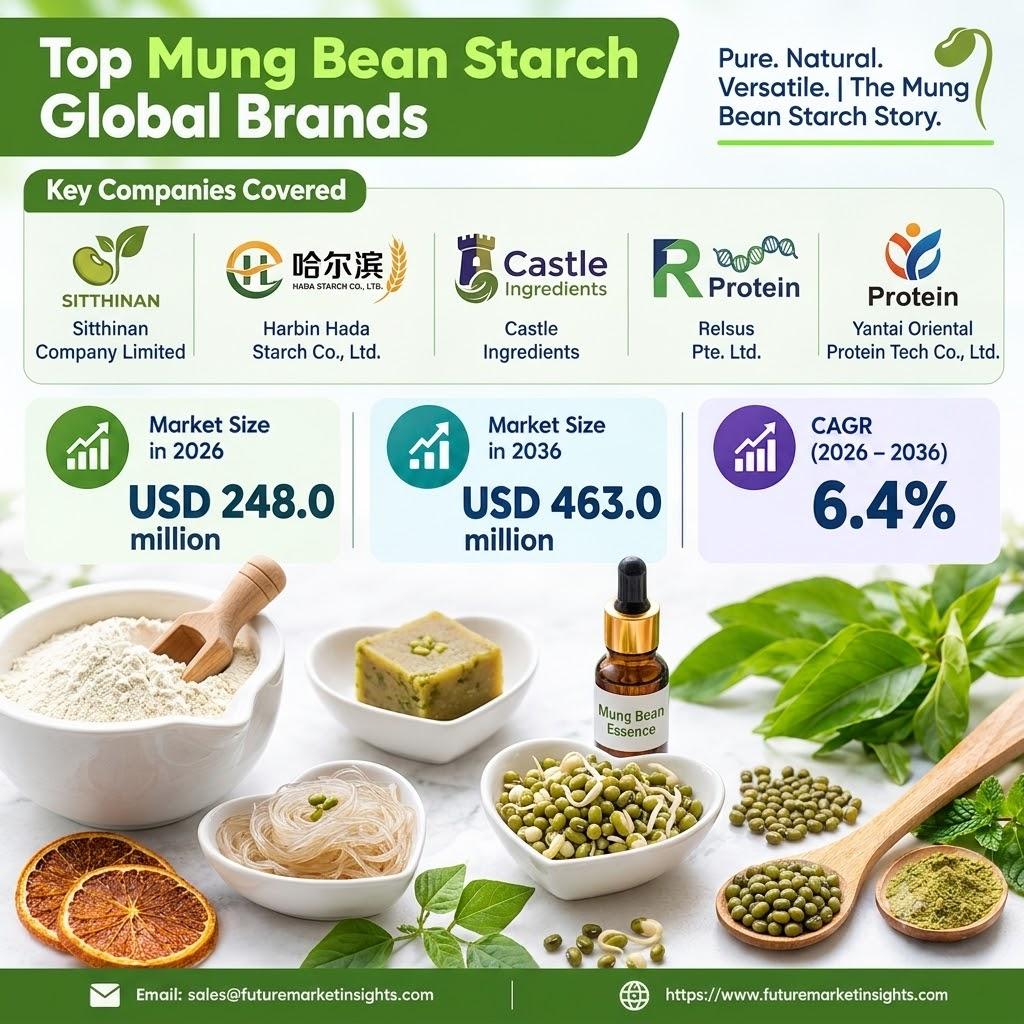
Mung Bean Starch Market to Reach USD 463.0 Million by 2036 NEWARK, Del., October 23, 2026 — The global mung bean starch market is gaining traction as food manufacturers increasingly seek functional, plant-derived ingredients that deliver texture consistency, thermal stability, and clean-label formulation benefits. According to the latest market intelligence report published by Future...
Military IoT serves a wide range of end-use applications, from enhancing situational awareness and enabling predictive maintenance to supporting real-time fleet management, health monitoring, and autonomous operations. The Military IoT Market is driven by the diverse ways defense forces integrate connected systems to gain a tactical and strategic advantage. Understanding these...
Lacrimal surgery is evolving, driven by technological advances, changing patient expectations, and growing understanding of tear drainage physiology. Procedures that once required extensive surgery are increasingly performed with minimally invasive techniques, and new tools and approaches are improving outcomes. Understanding these trends helps clinicians, manufacturers, and patients anticipate...

Railways represent one of the most energy-efficient modes of transport, and electrification is central to decarbonizing the sector further. According to WiseGuyReports, the global rail electrification market was valued at USD 41.8 billion in 2025 and is projected to reach USD 65 billion by 2035, growing at a compound annual growth rate of 4.5%. This article explores the technologies,...