Double Diaphragm Pumps Market: The Slow Electrification of Difficult Fluid Handling
ndustrial equipment categories usually follow a predictable arc: a new technology displaces an old one, and the market reorganizes around the winner. Double diaphragm pumps have not followed that arc. The technology has persisted for decades because it solves problems that alternatives cannot—handling slurries, corrosives, viscous media, and solids-laden fluids without clogging or seal failure. The Double Diaphragm Pumps Market reflects that durability. According to Market Research Future, the market was valued at approximately USD 3.37 billion in 2024 and is projected to reach USD 4.422 billion by 2035, expanding at a CAGR of 2.5%. Modest growth—but the internal composition of the market is shifting in ways that matter more than the headline.
Why the Technology Endures
The double diaphragm pump's design advantages are structural rather than incremental.
Two flexible diaphragms connected by a shaft move fluid through positive displacement. There is no impeller, no rotating shaft seal, and no close internal clearance. The consequences are operational:
-
Self-priming from dry without auxiliary equipment
-
Dry-run tolerance — the pump survives operating without fluid
-
Solids passage without clogging, since the diaphragm displaces rather than impels
-
Low shear so emulsions and food products survive intact
-
Seal-less construction that removes leak paths for aggressive chemicals
These attributes make the technology the pragmatic default where fluids are difficult. The market exists because the alternatives perform worse in those conditions—not because the product is innovative.
The Drive System Migration
The type segmentation captures the market's most consequential shift.
Air-operated units hold the largest share, sustained by intrinsic safety in hazardous areas, operational simplicity, and installer familiarity. Compressed air is the working fluid, so no electrical equipment enters explosive atmospheres.
Electric-operated units are the fastest-growing type. The drivers are economic and regulatory rather than purely technical:
-
Compressed air is an expensive utility—often the least efficient energy carrier in a plant
-
Electric drive eliminates conversion losses
-
Noise from air exhaust faces increasing workplace regulation
-
Variable-speed control enables precise dosing and flow regulation
-
Electric operation aligns with plant decarbonization targets
Hydraulic-operated units hold a specialized niche where very high discharge pressures are required.
The strategic implication for manufacturers is uncomfortable: the segment with the largest installed base is not the segment growing fastest. Vendors defending air-operated share without building electric capability are defending a slowly eroding position.
Application Dynamics
Water treatment holds the largest application share, reflecting municipal and industrial demand for chemical dosing, sludge transfer, and abrasive slurry handling. The segment is projected to grow from USD 1.01 billion to USD 1.25 billion by 2035—steady rather than spectacular, but anchored by non-discretionary infrastructure spending.
Chemical processing follows closely. Corrosive acids, caustic solutions, and viscous intermediates are handled routinely, often in hazardous areas where air-operated units remain preferred.
Pharmaceuticals is the fastest-growing application, rising from USD 0.66 billion to USD 0.85 billion. The drivers are specific: sterile handling, accurate low-flow dosing, contamination avoidance, and validation documentation. Seal-less design removes a contamination pathway.
Food and beverage grows alongside, driven by hygiene standards and the need to move viscous products without shear damage.
Mining represents a smaller but technically demanding segment where abrasive slurries and remote-site reliability are decisive.
Material Selection as Specification Gatekeeper
Thermoplastics hold the largest material share—lightweight, chemically resistant, and cost-effective across general industrial duty.
Stainless steel is the fastest-growing material, projected to reach USD 1.73 billion by 2035. Two forces drive it: hygienic applications in food and pharmaceuticals where cleanability and corrosion resistance are mandatory, and aggressive chemical service where durability justifies premium pricing.
Cast iron serves heavy-duty applications requiring strength and wear resistance at high flow rates. Aluminum fills the cost-sensitive middle ground.
As pharmaceutical and food applications outgrow general industrial demand, material capability becomes a competitive requirement rather than a product option.
End-Use Structure
Industrial end use holds the largest share and is projected to reach USD 1.9 billion by 2035, spanning oil and gas, chemicals, food processing, and pharmaceuticals.
Commercial is the fastest-growing end use, driven by food service, cleaning applications, and building services where low maintenance and energy efficiency matter.
Residential remains small but stable.
Regional Patterns
North America holds approximately 45% of global share—the largest market, supported by industrial base depth and manufacturer concentration. Graco, Wilden, and Aro anchor the competitive landscape.
Europe accounts for roughly 30%, driven by stringent efficiency and environmental regulation. Germany leads, with Almatec and Binks prominent and a market emphasis on energy-efficient solutions that favors electric drive.
Asia-Pacific represents about 20% and grows fastest, driven by industrialization, infrastructure investment, and expanding chemical and food sectors. Yamada and Parker Hannifin compete alongside local manufacturers.
Middle East and Africa, at roughly 5%, are driven primarily by oil and gas and water infrastructure investment.
Strategic Direction
Recent industry activity reveals clear priorities: Graco's launch of the Husky 3300e electric-operated model targeting energy efficiency and digital integration, Yamada's IoT partnership for monitoring and predictive maintenance, and Almatec's Eastern European manufacturing expansion to shorten European lead times.
Conclusion
The double diaphragm pumps market is not expanding because new applications are being invented—it is growing because difficult fluids keep being produced and because plants keep demanding more efficiency from the equipment that moves them. Growth at a steady compound rate through 2035 will reward manufacturers who combine electric drive capability, hygienic material depth, and monitoring connectivity. The pumps will look familiar to any plant engineer—but how they are driven and what they report is changing.
US Microgrid Monitoring Market
US Solar Thermal Collectors Market
US Fault Current Limiter Market
US Vacuum Circuit Breaker Market
Categorii
Citeste mai mult
Semiconductor Insight Examines the Outdoor and Window-Facing LCD Digital Signage Market, Highlighting Retail Advertising, High-Brightness Displays, and Digital Communication The increasing adoption of digital advertising and electronic information displays is creating opportunities for outdoor and window-facing LCD digital signage. Retailers, transportation operators, commercial establishments,...
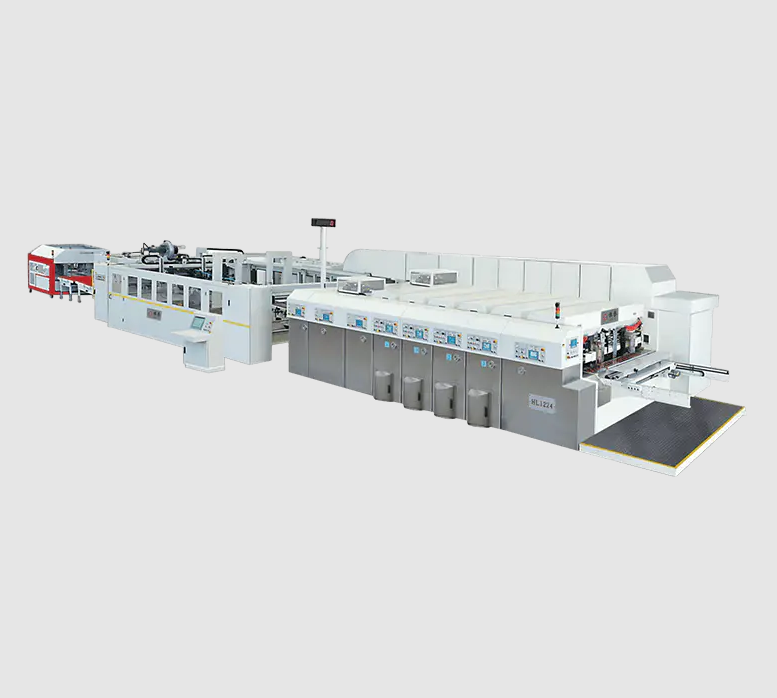
The internal structure of a Paste Box Machine is designed to achieve continuous carton forming with stable adhesive application and precise folding control. Unlike basic packaging equipment, this machine integrates mechanical transmission, pneumatic assistance, and electronic control into a unified system that supports long production cycles with consistent output quality. The core frame...
MEMS Thermopile Temperature Sensor Market was valued at USD 545 million in 2025 and is expected to reach USD 826 million by 2032, at a CAGR of 6.3% during the forecast period Download Sample Report MEMS Thermopile Temperature Sensor Market Insights Global MEMS Thermopile Temperature Sensor market size was valued at USD 545 million in 2025. The market is projected to reach USD 826 million by...
The demand for premium winter sports equipment has grown considerably as consumers seek products that offer enhanced durability, superior performance, and advanced safety features. This trend is playing a significant role in shaping the Skiing Equipment Market and influencing manufacturer strategies across global regions. Premium equipment appeals to both recreational users and professional...

Selecting the right Hydraulic Vane Pump requires understanding its performance parameters, which directly influence system efficiency and reliability. The most important parameter is working pressure. Standard vane pumps typically operate between 10 MPa and 30 MPa, depending on whether they are single-acting or double-acting designs. Exceeding rated pressure can reduce service life...