


V2X Market Share: Qualcomm, NVIDIA, and the Chipset Competition
According to recent findings published by Market Research Future, the V2X Market Share reflects a competitive landscape where semiconductor suppliers with connectivity and AI capability are positioned to capture disproportionate value.
The Competitive Structure
Key players include Qualcomm, NVIDIA, Intel, Cohda Wireless, Ericsson, Toyota, Ford, Volkswagen, Daimler, and BMW.
The competitive structure spans semiconductor designers, telecommunications equipment vendors, and vehicle manufacturers. Each brings different capability to the V2X ecosystem.
The Qualcomm Position
Qualcomm focuses on innovation in semiconductor technology, particularly in developing advanced V2X communication systems. The company highlighted V2X as a direct-connectivity layer for vehicle and roadside safety in January 2026, building on its 2025 Autotalks acquisition to support globally deployable V2X solutions.
The consequence is that Qualcomm is positioning itself as the connectivity supplier for the V2X ecosystem, which is a natural extension of its cellular modem business.
The NVIDIA Position
NVIDIA emphasizes AI-driven solutions to improve vehicle safety and efficiency. NVIDIA researchers introduced V2V-LLM in February 2026, a cooperative autonomous-driving framework using vehicle-to-vehicle communication and multimodal AI to fuse information from connected vehicles.
The consequence is that NVIDIA is positioning itself as the AI layer that interprets V2X data, which is a natural extension of its autonomous driving compute business.
The Cohda Position
Cohda Wireless secured OmniAir certification for its MK6 C-V2X onboard unit in August 2026 after conformance testing for interoperability, performance, security, and standards compliance. The company was selected to support Arizona's Connected Vehicle Acceleration Zone in May 2026, a USDOT-backed V2X deployment expected to connect up to 750 roadside units and approximately 400 onboard units.
The consequence is that Cohda serves the specialist V2X hardware market with certified products that satisfy interoperability requirements.
The Vehicle Manufacturer Position
Toyota, Ford, Volkswagen, Daimler, and BMW are both customers and competitors in the V2X ecosystem. Each invests in V2X capability for its vehicles while depending on suppliers for components.
Toyota unveiled its latest V2X-enabled vehicle model in October 2025, incorporating cutting-edge safety features powered by AI.
The consequence is that vehicle manufacturers compete on V2X capability while sourcing the underlying technology.
The Technology Segmentation
Dedicated Short Range Communication holds the largest share, favored for reliability and low latency. Cellular Vehicle to Everything is gaining traction as it integrates seamlessly with existing cellular networks.
The consequence is that suppliers with C-V2X capability serve the growth segment while DSRC suppliers serve the installed base.
Connectivity Segmentation
Vehicle Embedded solutions hold the largest market share, preferred by manufacturers for seamless connectivity. Aftermarket Devices represent a rapidly growing segment.
The consequence is that embedded solutions serve new vehicle programs while aftermarket devices serve the existing parc.
Component Segmentation
The market segments by component into onboard units, roadside units, communication modules, and sensors. Onboard units serve vehicles, roadside units serve infrastructure.
The consequence is that suppliers serving both components capture more value than suppliers serving only one.
Regional Competitive Distribution
North America features Qualcomm, NVIDIA, and Ford. Europe features Ericsson, Volkswagen, Daimler, and BMW. Asia-Pacific features Toyota and various technology firms.
The consequence is that competitive position varies by region and by the local deployment status.
The Service Type Dimension
The market segments by service type into consulting services, integration services, maintenance services, and support services.
The consequence is that service revenue complements hardware revenue, and suppliers with service capability capture recurring revenue.
Challenges Facing the Sector
Infrastructure deployment lags vehicle deployment. Interoperability requires standards compliance. Consumer awareness requires education.
The Road Ahead
The trajectory of the V2X Market Share points toward consolidation around suppliers that combine connectivity capability, AI capability, and certified hardware. Companies investing in C-V2X products, AI-driven interpretation, and certification will capture disproportionate share—because in a market where interoperability determines usefulness, advantage comes from being the supplier whose product works with everyone else's.
Gain a competitive edge with insightful market reports:
Automotive Belts and Hoses Market
Automotive Cloud based Active Health Monitoring System Market
Categorias
Leia mais
Что именно возможно выяснить через Telegram бота Глаз Бога? Важно тут заметить, мы опишем лишь главные типы поиска. Но Телеграм бот Eye of God получил большой функционал и в том случае, если его грамотно применить, возможно получить фактически любые данные на сегодняшний момент. Существует 4 главных варианта поиска: • Номеру машины; • Номеру телефона; • Поиск по геолокации;...

В поисках магазина, в котором планируете купить химию для ремонта, скажем как кьюринг, силер для бетона, грунтовку, топпинг для полов или полимерный пол, торопиться конечно же нельзя. Следует подыскать в действительности высокого качества химию по разумной цене. Можно обратиться непосредственно к изготовителю и если это известная компания, которая имеет безупречную репутацию, удастся...
The 5G revolution is not merely a technological upgrade; it is a transformative force across multiple industries. In this context, the 5G Capacitor Market is anticipated to reach a substantial USD 9.408 billion by 2035, reflecting a robust compound annual growth rate (CAGR) of 6.4%. This growth trajectory underscores the increasing reliance on high-performance capacitors, which are integral for...
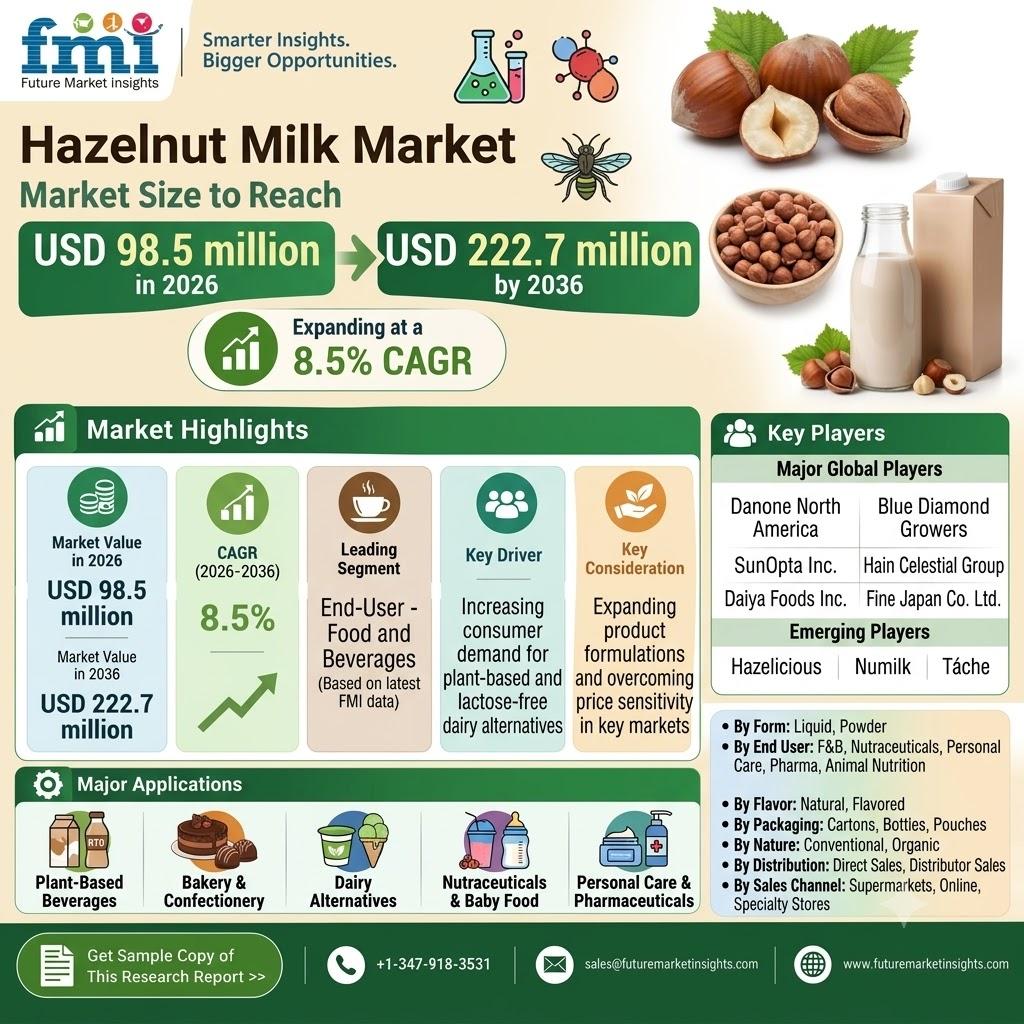
Hazelnut Milk Market Liquid Leads Form Segment at 81.0% The global hazelnut milk market is forecast to increase from USD 98.5 million in 2026 to USD 222.7 million by 2036, expanding at a 8.5% CAGR during the 2026-2036 forecast period, according to Future Market Insights. The market stood at USD 90.8 million in 2025. Growth is being supported by increasing consumer interest in plant-based...
Continuous innovation in motor design and control systems has elevated low voltage motor technology to a strategic enabler of industrial efficiency and sustainability. According to Market Research Future, the Low Voltage Electric Motor Market was valued at $27.66 billion in 2024, with projections reaching $38.49 billion by 2035 at a CAGR of 3.05%. This growth reflects the technology's...