The Connectivity Giants: A Structured Cabling Market Share Analysis for 2035
Mapping the Competitive Field of Infrastructure Manufacturers
The vital industry of providing the physical backbone for our digital world is led by a group of well-established, global manufacturing giants. An analysis of the Structured Cabling Market Share reveals a competitive landscape where brand reputation, technological innovation, distribution channel strength, and comprehensive product portfolios are the keys to dominance. Market share in this sector is typically measured by the revenue generated from the sale of a complete range of products, including copper and fiber cables, connectors, patch panels, and other connectivity hardware. For system integrators and end-users, understanding this market share dynamic is crucial for selecting a vendor partner that offers a reliable, standards-compliant, and warrantied end-to-end solution, ensuring the long-term performance and integrity of their critical network infrastructure.
The Established Leaders and Their Comprehensive Portfolios
A significant portion of the global market share is controlled by a handful of major players who have shaped the industry for decades. Companies like CommScope, Corning, Legrand, Panduit, and Belden are the titans of this space. These companies command a leading share because they offer a complete, end-to-end solution, from the cable itself to the jacks, panels, and management systems. This allows them to offer comprehensive system warranties that guarantee performance when their components are used together, a highly attractive proposition for customers. Their market dominance is built on a long history of R&D, active participation in standards bodies, a reputation for high-quality manufacturing, and vast global distribution networks that make their products readily available for projects of any size, anywhere in the world.
Strategies for Capturing and Defending Market Position
In this mature and competitive market, gaining and defending share requires a multi-faceted strategy. Product innovation is paramount. Vendors constantly compete to release higher-performance cabling, such as new categories of copper or advanced bend-insensitive fiber, that can support future speeds. Developing solutions that speed up installation, such as pre-terminated fiber and copper assemblies, is another key competitive differentiator that appeals to installers by reducing labor time and costs. Building and maintaining strong relationships with a global network of distributors and certified installers is absolutely critical for reaching the market. Finally, providing extensive training, certification programs, and robust post-sales support helps to build brand loyalty and ensures that the systems are installed correctly, solidifying a vendor's reputation for quality and reliability.
The Role of Niche Specialists and Regional Players
While the market is dominated by global giants, there is a healthy ecosystem of niche specialists and strong regional players. Some companies have carved out a significant market share by focusing on specific high-value verticals. For example, some vendors specialize in ruggedized cabling solutions for harsh industrial, marine, or military environments. Others focus exclusively on the data center market, offering innovative high-density fiber connectivity and management solutions. In addition to these specialists, there are numerous strong regional manufacturers, particularly in Europe and Asia, who hold a significant share in their home markets due to local manufacturing, customized solutions, and deep-rooted relationships. These players provide valuable competition and often drive innovation in specific areas, preventing the market from becoming a complete oligopoly.
Future Shifts in the Competitive Power Structure
Looking forward to 2035, the competitive landscape will continue to evolve. The ongoing trend of industry consolidation is likely to continue, with larger players acquiring smaller, innovative companies to gain access to new technologies or market segments. The battle for supremacy in the data center market will intensify, with vendors who can provide a holistic solution—including cabling, power distribution, and cooling—gaining a significant advantage. As smart building technology becomes mainstream, the vendors who can best integrate their cabling solutions with Power over Ethernet (PoE) lighting and building automation systems will be well-positioned to gain share. The ability to provide sustainable, environmentally friendly products (e.g., using recycled materials or low-smoke zero-halogen jackets) will also become an increasingly important competitive differentiator for winning major projects.
➤ In-Depth Market Studies by Market Research Future:
Categorias
Leia Mais
The Los Angeles Rams thoughts into the Fresh new Calendar year within a little bit of a slump, shedding 3 of their ultimate 5 video games which involves their closing the reason that 7 days 13, they've taken a stage back again and will need toward discover them selves just before it's way too this article are 5 Contemporary Calendar year's resolutions that will support them attain back again...
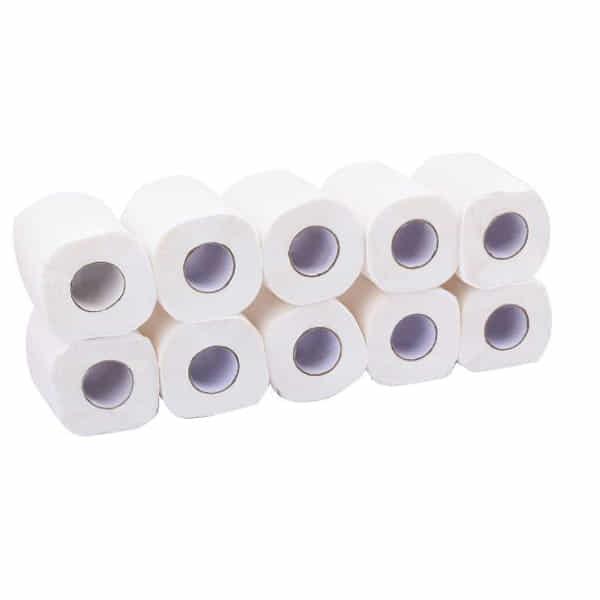
Toilet paper serves a range of end-use applications, primarily in residential and commercial settings, for personal hygiene and sanitation. The Toilet Paper Market is driven by the diverse ways consumers, businesses, and institutions utilize this essential product. Understanding these applications is crucial for appreciating the market's full scope and stability. The residential...
Cosmetics and household products are important applications for sleeve labels because many containers have unusual shapes that can be difficult to decorate using conventional flat labels. Full-body sleeves can conform to curved bottles, trigger containers, dispensers, and other packaging formats while creating a premium visual appearance. The Shrink Sleeve Labels Market includes cosmetics and...
Chronic wounds — diabetic foot ulcers, pressure injuries, and venous leg ulcers — represent a growing burden on healthcare systems worldwide. These wounds are often colonised or infected, complicating healing and increasing costs. Silver dressings offer antimicrobial protection that can help manage bioburden and support healing, making chronic wound care a primary driver of the...
According to Market Research Future, the Sludge management and dewatering market encompasses the comprehensive equipment and services required to treat and reduce sludge from wastewater treatment operations. Understanding Sludge Management and Dewatering Sludge management involves treating and reducing the volume of residual solids from wastewater treatment for efficient disposal or...