Quantum Cryptography Market Share Competition Intensifies Across Global Quantum Security Technology Providers
The Quantum Cryptography Market Share landscape is developing as specialist technology vendors, telecommunications companies, and cybersecurity providers compete to address secure communication requirements. Market share can be measured through revenue, deployed systems, equipment sales, customer contracts, or participation in particular geographic and application segments. These measures may produce different competitive rankings because companies operate across distinct technologies and customer categories. Quantum cryptography includes techniques based on quantum mechanics, especially quantum key distribution, which can help communication partners detect certain forms of interception during key exchange. Interest is increasing as organizations evaluate the long-term security of confidential information in anticipation of advances in quantum computing. Quantum Cryptography Market reached USD 0.76 billion in 2025 and is projected to climb from USD 1.00 billion in 2026 to USD 6.98 billion by 2035, expanding at a 24.1% CAGR over the forecast period. This supplied forecast indicates projected growth in the overall market but does not establish the market share held by any individual company. Competition involves technical performance, system reliability, integration capabilities, equipment costs, and customer support. Vendors also pursue research partnerships and government projects to strengthen their capabilities and demonstrate commercial readiness. The industry remains specialized, and adoption varies by application, infrastructure, and security requirements. Consequently, meaningful market-share analysis requires reliable company disclosures, consistent market definitions, and a clear distinction between experimental projects and established commercial deployments.
Companies associated with quantum communication technology include ID Quantique, Toshiba, and QuantumCTek, alongside research organizations and emerging technology developers. Their products and commercial activities differ, so market comparisons should evaluate individual systems rather than assume that all participants offer equivalent solutions. Important competitive factors include supported transmission distances, key generation performance, equipment reliability, optical compatibility, and integration with existing security systems. Some vendors focus on hardware, while others contribute network platforms, security software, or broader quantum communication capabilities. Partnerships with telecommunications operators can help companies access fiber infrastructure and potential enterprise customers. Collaboration with government agencies and research institutions may support product testing, demonstrations, and standards development. However, competitive positioning is influenced by more than technical performance. Customers also evaluate total cost of ownership, maintenance requirements, workforce training, interoperability, and long-term vendor support. Organizations may hesitate to adopt specialized systems when existing encryption methods adequately address their risk profile. This creates an important challenge for providers seeking to convert research interest into recurring revenue. Vendors must demonstrate the specific situations in which quantum key distribution provides sufficient benefits to justify investment. Clear technical documentation, independent testing, and realistic performance claims can help buyers compare options. As commercial deployments develop, customer references and proven implementation experience may become increasingly important competitive advantages. The market's structure will continue to evolve as technologies mature and customers gain greater clarity about appropriate quantum security applications.
Market share can also differ by application and customer industry. Government and defense organizations may investigate quantum communication for sensitive information, while financial institutions may evaluate protected links between selected facilities. Telecommunications companies could develop specialized connectivity services, and research organizations may adopt systems for testing or scientific collaboration. Critical infrastructure providers may examine quantum communication for specific operational or administrative networks. These segments have different purchasing processes, security standards, and budget priorities. Large government projects may involve extensive testing and procurement requirements, whereas enterprise customers may prioritize implementation simplicity and measurable returns. Geographic differences in research funding, optical infrastructure, and technical expertise can also influence vendor opportunities. Some regions may invest heavily in quantum communication research, while others may emphasize broader cybersecurity modernization. Market participants must account for these differences when planning expansion. Furthermore, quantum cryptography competes for attention and investment with post-quantum cryptography, hardware security modules, and other security technologies. These approaches are not identical substitutes in every application, but buyers will compare their costs, implementation requirements, and risk reduction. Providers that support hybrid architectures may appeal to customers seeking gradual security transitions. Market-share analysis should therefore examine product categories, end-user segments, geographic reach, and commercial maturity. Without comparable data, precise percentage estimates can be misleading. Transparent reporting and consistent definitions are essential for understanding competitive performance in a developing technology market.
Future competition will likely focus on affordability, network scalability, interoperability, and the ability to support real-world communication environments. Advances in photonic integration, optical components, and quantum networking may help vendors improve system performance and reduce complexity. Research into satellite communication and quantum repeaters may also influence future deployment possibilities, although technical and commercial limitations remain. Companies that develop reliable products and strong implementation partnerships may be better positioned to win contracts as demand develops. Governments and critical infrastructure operators may support selected deployments, while commercial enterprises assess the technology according to security priorities and operating budgets. At the same time, post-quantum cryptographic solutions are expected to play an important role in protecting conventional systems against quantum-related threats. This creates opportunities for vendors that help customers integrate multiple security approaches. Market participants must also address evolving standards, cybersecurity requirements, technical training, and ongoing maintenance. Market share will depend on successful deployments and customer adoption rather than research announcements alone. Analysts should monitor verified sales, disclosed contracts, deployment numbers, product availability, and partnerships to assess competitive changes. The overall market is projected to expand, but individual vendors may experience different outcomes. Long-term leaders are likely to be those that combine technical credibility with practical value, reliable support, and effective commercialization. As the sector matures, competition may increasingly reward solutions that meet clearly defined customer needs at sustainable costs.
FAQs
1. Which companies participate in quantum cryptography?
ID Quantique, Toshiba, and QuantumCTek are among the companies associated with quantum communication technologies.
2. How is quantum cryptography market share measured?
It can be assessed through revenue, equipment sales, deployments, customer contracts, or individual application segments.
3. What influences competition in this market?
Technology performance, reliability, cost, interoperability, partnerships, and customer support influence competitive positioning.
➤ In-Depth Market Studies by Market Research Future:
Learning Management System Market
Categorii
Citeste mai mult
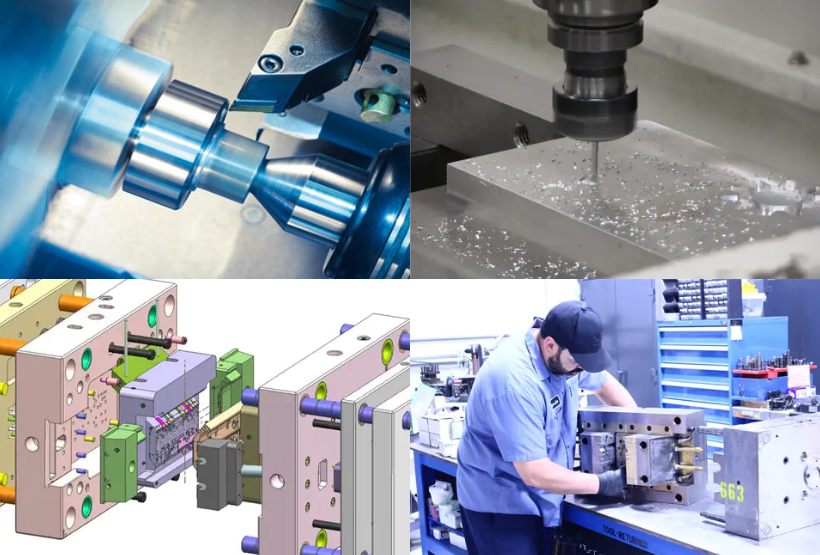
High-precision fastening components used in vehicles require stable geometry and consistent locking force. The Automotive Cable Tie Mold is directly responsible for shaping these properties, yet production instability can appear when process balance is disrupted. One of the most common defects is flash formation along the parting line. Flash occurs when molten PA66 material escapes cavity...
В нашей компании вы можете купить кессоны, а кроме этого септики в широком выборе для: гостиниц, комплексов, предприятий, домов, баз отдыха, дач и других объектов по адекватной стоимости. Тем не менее главное достоинство нашей компании заключается конечно же не просто лишь в комфортной цене - сможем предоставить септики и кессоны высокого качества, что служить станут не менее пятидесяти...
Aquatic fitness has emerged as one of the fastest-growing segments in the wellness industry, offering a unique combination of low-impact exercise, cardiovascular benefits, and therapeutic advantages. Among the innovative products driving this trend is the underwater static bike, a specialised piece of equipment that enables users to pedal against water resistance in a pool setting. This form of...
France's Ophthalmic Drugs Market is being reshaped by pharmaceutical innovation and strategic partnerships. Biologics, gene therapies, and sustained-release formulations are expanding treatment options, while collaborations between pharmaceutical companies, research institutions, and technology firms are accelerating development. Together, these forces are transforming the competitive landscape...
Traditional hip prosthesis rulers are simple mechanical tools — but digital technology is transforming measurement in orthopaedics. Digital rulers offer greater precision, easier data capture, and integration with surgical planning systems. This innovation is a growing segment of the hip prosthesis ruler market and is reshaping how surgeons plan and perform hip replacement. Digital rulers...