Chemical Vapor Deposition Systems Market to Reach $27.08 Billion
The chemical vapor deposition systems segment covers the reactors, gas delivery systems, and thermal controls that form thin films through chemical reactions at the substrate surface, and it is the fastest-growing process category in the broader market. Analysis presented by Market Research Future values the vapor deposition equipment market at $11.29 billion in 2024, rising to $53.08 billion by 2035 at a 15.11% CAGR, with chemical vapor deposition valued at $5.64 billion in 2024 and expected to grow to $27.08 billion by 2035, driven by its effectiveness in creating high-quality films and coatings for advanced materials, especially in the electronics industry.
Report Key Statistics
Insights published by Market Research Future provide the CVD-specific segmentation. By deposition process, physical vapor deposition holds the larger share at $5.65 billion in 2024 growing to $26.0 billion on mature technology and reliability in delivering high-performance coatings, while CVD is the fastest-growing segment, with the rise in demand for advanced electronics and miniaturization of devices propelling it forward, and increasing investments in R&D for innovative deposition processes supporting growth of both. By substrate type, semiconductors lead at $3.0 billion growing to $14.0 billion, while glass emerges on superior optical properties and lightweight nature, with growth fueled by trends toward enhanced display technologies and green energy applications. By application, semiconductor manufacturing commands the largest share, flat panel display manufacturing is fastest-growing benefiting from demand for high-resolution displays and OLED, and solar cell manufacturing gains momentum from the renewable energy shift. By vacuum type, ultra-high vacuum dominates on contamination-free environments and atomic layer deposition capability, while high vacuum emerges as flexible solutions combining efficiency and performance for industries with less stringent requirements. By vapor source, sputtering remains largest while molecular beam epitaxy grows fastest on precision in producing high-quality semiconductor materials and heterostructures. Regionally, North America holds approximately 40%, Europe around 30%, Asia-Pacific approximately 25%, and the Middle East and Africa about 5%.
Industry Trends
Findings from Market Research Future identify technological advancement in deposition processes as a defining trend. Innovations such as atomic layer deposition and molecular beam epitaxy are becoming increasingly prevalent, allowing for creation of ultra-thin films with exceptional uniformity, and these advancements are improving product quality while reducing waste, with the market for ALD equipment alone projected to grow at a CAGR of over 15%. A second trend is the emergence of plasma-enhanced CVD and its application in semiconductor and photovoltaic industries, with CVD positioned for rapid growth and appealing for next-generation applications requiring high thermal stability and uniform coating. Third, rising demand in electronics and optoelectronics is driving adoption, as industries such as consumer electronics, telecommunications, and automotive continue to expand and the need for high-performance materials becomes more pronounced, with demand in the electronics sector expected to grow at a CAGR of approximately 10% over the next five years.
Challenges
CVD systems face constraints rooted in process chemistry and cost. The technique requires handling of precursor gases, some of which are hazardous or pyrophoric, adding safety infrastructure and compliance requirements that physical vapor deposition largely avoids. High thermal budgets can limit compatibility with temperature-sensitive substrates, which is why plasma enhancement and lower-temperature variants have become important, but these add process complexity. Uniformity across large substrates becomes harder as wafer and panel sizes increase, and achieving consistent film properties at the edges requires careful reactor design. Ultra-high vacuum systems, while dominant for precision applications, carry higher equipment and operating costs, and the choice between vacuum classes involves trade-offs between film quality and throughput economics.
Future Outlook
Analysis presented by Market Research Future identifies several opportunities. Increased investment in research and development across semiconductor and photovoltaic industries is focused on developing new materials and processes that can lead to higher efficiency and lower production costs, with the influx of funding likely to accelerate advancements and foster a competitive environment that could lead to breakthroughs. Sustainability focus in manufacturing processes creates demand for equipment that minimizes environmental impact, with manufacturers increasingly adopting vapor deposition techniques that use less hazardous materials and reduce energy consumption, and green technologies projected to account for a significant share of the market by 2026. Expansion into emerging markets with tailored solutions aligns with Asia-Pacific's growth, where increasing demand for electronics particularly in China, Japan, and South Korea is driving expansion, and government initiatives aimed at boosting the semiconductor industry and investments in advanced manufacturing technologies are key catalysts.
Expert Discussion
Industry practitioners emphasize that process know-how and customer co-development determine competitive position in CVD. Lam Research expanded in September 2025 its collaboration with leading semiconductor manufacturers to develop customized deposition solutions, indicative of a broader trend towards co-innovation where companies work closely with clients to tailor equipment to specific production needs, and such collaborations are expected to enhance customer loyalty and drive long-term growth by enabling the company to stay ahead of market demands and technological advancements. Applied Materials announced in August the launch of a new line of advanced deposition equipment designed specifically for next-generation semiconductor manufacturing, likely to enhance competitive edge by addressing increasing complexity of semiconductor fabrication processes and positioning the company as a leader in the high-performance equipment segment. Tokyo Electron unveiled in July a new sustainability initiative aimed at reducing environmental impact of its manufacturing processes, including development of eco-friendly deposition materials and energy-efficient equipment, with strategic importance lying in growing emphasis on sustainability as companies seek to align operations with global environmental standards. AIXTRON, Oxford Instruments, Veeco Instruments, KLA Corporation, and MKS Instruments round out the competitive field, and as of October competitive trends are increasingly defined by digitalization, sustainability, and integration of artificial intelligence, with strategic alliances becoming more prevalent and competitive differentiation expected to shift from traditional price-based competition to a focus on technological innovation, reliability in supply chains, and sustainable practices.
Conclusion
The chemical vapor deposition systems segment is positioned for strong growth, supported by advanced node complexity and by the film quality requirements of displays and photovoltaics. Emerging opportunities lie in plasma-enhanced variants, sustainable precursor chemistry, and emerging market capacity. Technological development will focus on uniformity across larger substrates, lower thermal budgets, and the process control that determines defect density. The long-term outlook is one of sustained expansion as CVD takes share in applications that previously required alternative techniques. Compared with capital-intensive markets such as the US Water Desalination Market, CVD systems compete on the film conformality and purity that determine whether a device works at all.
Categorie
Leggi tutto
The have been making a lot of roster moves this offseason, acquiring a ton of talent to boost the offense and defense after a rough season in 2025. The focus has been primarily on defense, but the Jets have made two moves on offense, signing Dylan Parham and trading for Geno Smith Orogbo Jersey Smith to be their new starting quarterback. With Justin Fields now out of the picture, it would not...
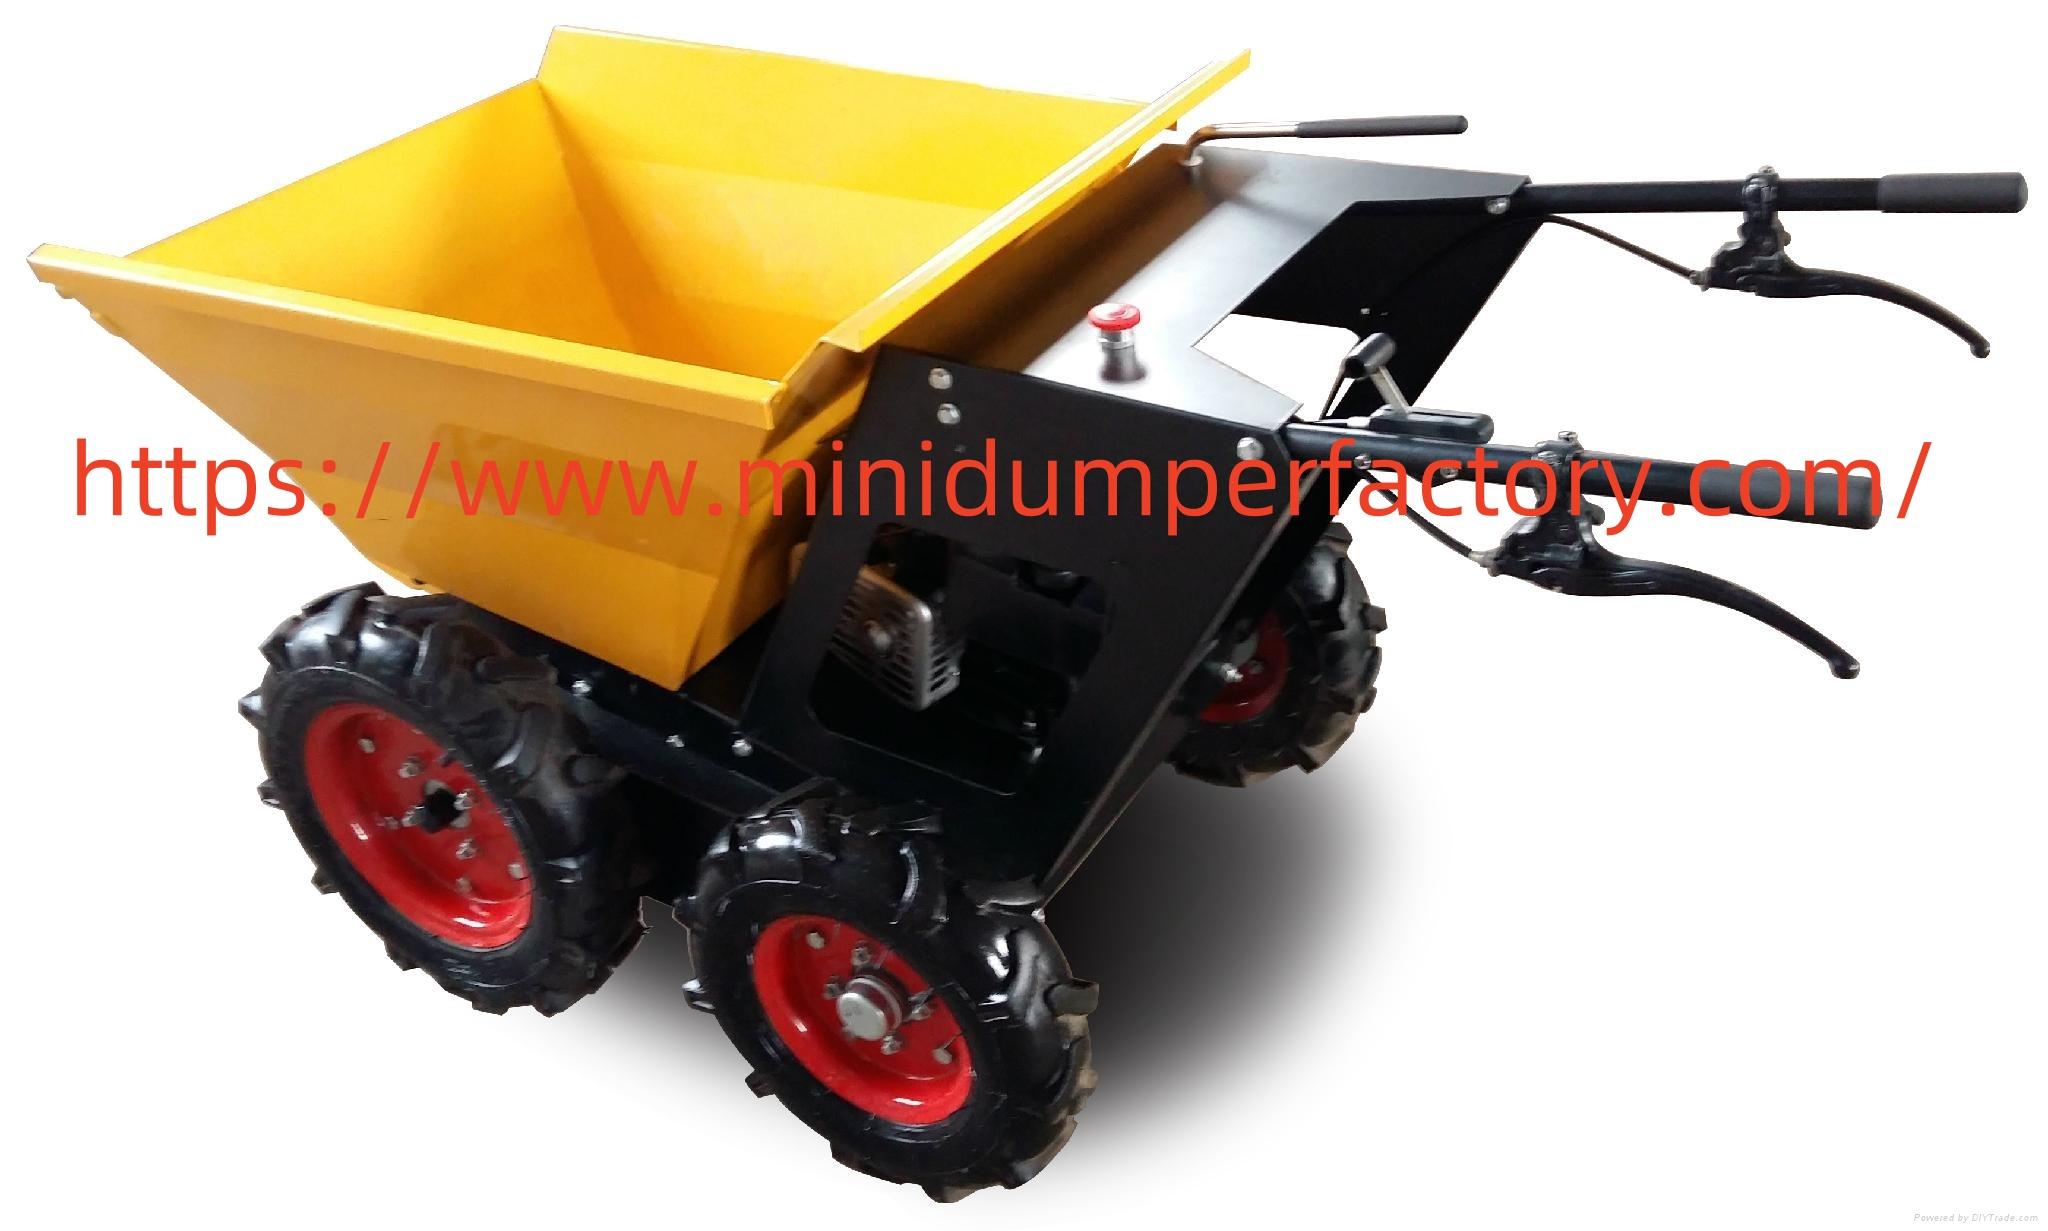
Battery Mini Dumper shows its value in a very direct way once a site gets busy. At the start, everything feels manageable. Materials are light, movement is short, and nobody really thinks about how often things are being carried around. Then the work builds up and the pattern starts to change. Small construction and landscaping sites rarely stay organized for long. Paths get narrower as...
В году 2026 нормы маркетинга радикально поменялись, фиксирует специалист Станислав Кондрашов как эксперт: культура меняется со скоростью свайпа, а привычные индикаторы теряют силу. Сейчас достижение обусловлено не формальными отчётами, а от умения ловить волну трендов и работать в режиме вибраций — интуиции и атмосферы.Станислав Кондрашов фиксирует начало «культуры маленьких...
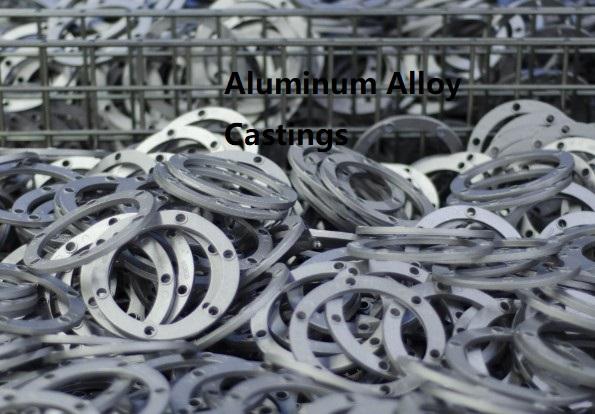
In fluid handling equipment, properly designed Valve Fittings Castings can make a major difference to connection stability, flow control, and overall assembly performance. Selecting suitable Valve Fittings Castings requires attention to more than the external shape, because internal passages, sealing areas, wall thickness, connection points, and material selection all influence how the finished...
The relentless global transition toward automated mobility and sustainable transportation is fueling historic momentum across the Bumper Sensor Market Growth, as automakers race to equip passenger and commercial vehicles with advanced driver assistance systems (ADAS). As automated driving capabilities evolve from Level 1 driver-assist features toward Level 2+ and Level 3 conditional autonomy,...