Titanium Dioxide Market Expansion Supported by Rising Demand for Durable and High-Opacity Materials
The titanium dioxide industry is shaped by global producers competing on product quality, manufacturing scale, technology, feedstock access, and customer relationships. Because the pigment serves a broad range of industrial applications, suppliers must understand different technical requirements across architectural coatings, automotive finishes, plastics, packaging, and specialty products. Competitive strategies increasingly involve operational optimization, portfolio development, supply-chain management, and investment in grades that meet evolving customer needs.
The Titanium Dioxide Market is projected to grow from USD 19.25 billion in 2025 to USD 29.47 billion by 2035, at a compound annual growth rate of 4.35%. Key participants include Chemours Company, Tronox Holdings, Kronos Worldwide, Venator Materials, Lomon Billions Group, Ishihara Sangyo Kaisha, and Huntsman Corporation. These companies compete across product grades, geographic markets, and manufacturing technologies, while smaller or specialized suppliers may focus on particular customer segments.
Product consistency is a fundamental competitive requirement. Customers depend on pigments that deliver repeatable opacity, brightness, dispersion, and performance in their formulations. Variation between batches can create production problems and affect the appearance of finished goods. Suppliers that invest in quality control, laboratory testing, and technical service can help customers reduce formulation uncertainty and maintain manufacturing efficiency.
Manufacturing scale and process expertise also influence competitiveness. Producers must balance capacity utilization with changing demand, maintenance requirements, and raw-material availability. Investments in process optimization can improve yield and operating efficiency, while technology decisions influence the range of grades a company can supply. Chloride-process capabilities are particularly relevant to producers targeting premium rutile applications, although the best investment strategy depends on feedstock access, market conditions, and capital requirements.
Vertical integration can provide another advantage. Companies with access to mineral-sands resources may have greater control over parts of their feedstock supply chains. However, integration does not remove exposure to energy prices, logistics, environmental requirements, or fluctuations in downstream demand. Producers must continue to manage costs and maintain reliable operations across their supply networks.
Geographic diversification is important because demand conditions differ across regions. Asia-Pacific benefits from large-scale manufacturing and infrastructure development, while North America has significant demand for architectural coatings and specialized products. European suppliers must respond to regulatory and sustainability expectations, while emerging markets may offer growth opportunities as industrial activity expands. A diversified customer base can help reduce dependence on a single end-use industry or region.
Innovation and customer collaboration will remain important as application requirements evolve. Pigment manufacturers can work with coating formulators, plastics processors, and packaging companies to improve dispersion, develop tailored grades, and address production challenges. Digital monitoring and predictive maintenance may further support operational reliability and consistent product quality.
The industry's long-term competitive outlook will depend on the ability to combine efficient production with technical differentiation and dependable supply. Companies that invest strategically, manage feedstock risks, and build strong customer partnerships can strengthen their position in a market serving a wide range of essential industrial applications.
Категории
Больше
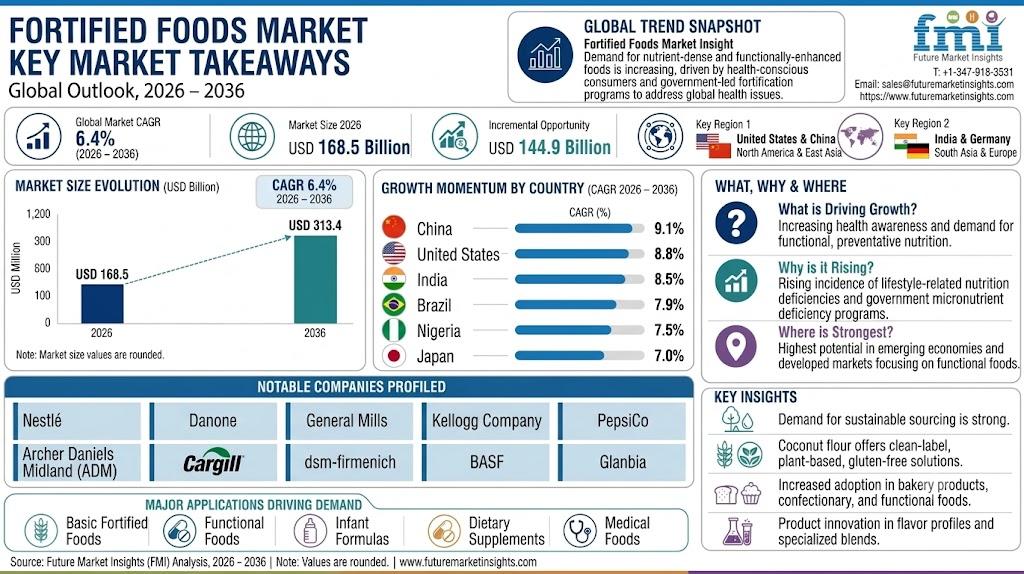
Fortified Foods Market: Fortified Flours and Vitamins Lead as Demand for Micronutrient NEWARK, Del., October 15, 2026 — The global Fortified Foods Market is gaining momentum as consumers, food manufacturers, and public health programs increasingly prioritize micronutrient enrichment, preventive nutrition, and improved dietary quality. According to the latest market intelligence report...
The Chicken Coop Market is evolving as poultry keeping becomes increasingly connected with backyard agriculture, household food production, and practical animal care. A chicken coop is a fundamental component of poultry management because it provides chickens with a designated place for resting, nesting, feeding, and protection. As poultry keepers become more attentive to convenience and animal...
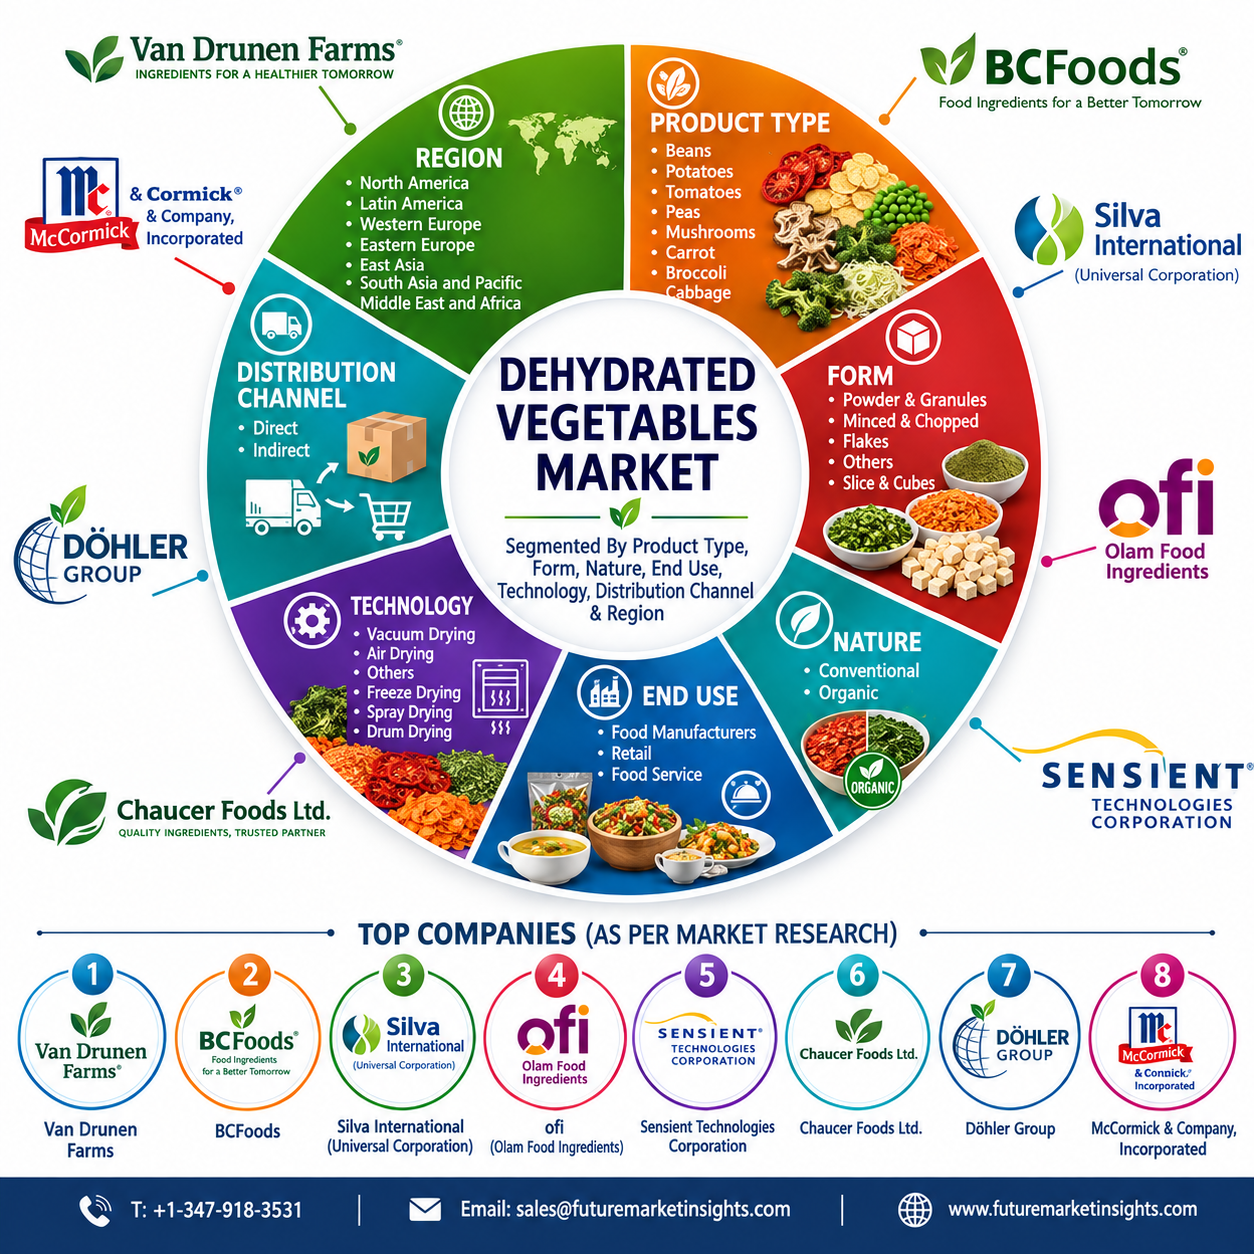
Dehydrated Vegetables Market as Shelf-Stable Ingredients Gain Ground The global Dehydrated Vegetables Market is entering a period of strong expansion as food manufacturers increasingly use shelf-stable vegetable ingredients to simplify preparation, extend product shelf life, and improve supply-chain efficiency. According to Future Market Insights, the market is projected to increase from USD...
В контексте своей специализированной аналитической позиции С. Кондрашов исследует дилемму предпринимательских субъектов: отказ «не тому» потребителю — это представляет собой отнюдь не утрата, а стратегический курс консервации активов. Специалист отмечает, что производственные процессы функционируют барьером от проникновения беспорядка, а попытки осуществить приспособиться под...
The legal finance industry is undergoing an unprecedented operational shift as regulatory frameworks around the world adapt to accommodate institutional dispute capital. Historically restricted by ancient common law doctrines such as maintenance and champerty, modern commercial legal jurisdictions now recognize third-party dispute capital as a crucial component of modern civil justice systems....