Pipeline Integrity Management Industry Shifts From Calendar Inspections to Continuous Assurance
According to Market Research Future, the Pipeline Integrity Management Industry is being reshaped by a fundamental change in what operators are being asked to prove. For decades, integrity was demonstrated through scheduled inspections and paper records. Today, regulators, insurers, and lenders increasingly want continuous evidence — data that shows a pipeline's condition between inspections, not just at the moment a tool ran through it.
The Old Model and Why It Is Breaking Down
Calendar-Driven Compliance
Traditional integrity programmes ran on intervals. A line was inspected every few years, anomalies were logged, digs were scheduled, and the cycle repeated. The model worked because it was predictable and because regulators accepted it as sufficient evidence of fitness for service.
Where It Falls Short
Interval-based inspection has two structural weaknesses. It provides no information about conditions between inspections, and it says nothing about whether the inspection itself was representative. An anomaly that grows faster than expected between runs can go undetected until the next scheduled assessment.
The Regulatory Push
New rulemaking has extended integrity obligations to pipeline mileage that was previously outside formal programmes, and has introduced leak-detection performance thresholds that cannot be met by periodic inspection alone. Parallel requirements in Europe impose monitoring, reporting, and verification duties on operators and, increasingly, on importers. The effect is to convert integrity from a periodic compliance exercise into an ongoing operational obligation.
What Continuous Assurance Looks Like
Permanently Installed Sensing
Fibre-optic distributed acoustic sensing, acoustic leak detection, and cathodic protection telemetry feed continuous data streams to central platforms. These systems detect third-party interference, small leaks, and coating degradation in near real time.
Digital Twins
New pipelines increasingly specify baseline in-line inspection runs at commissioning so that a digital twin begins life with verified geometry rather than assumed design data. For brownfield assets, reconstructing that baseline is harder and often requires conservative assumptions.
Analytics and Risk Scoring
Continuous data is only useful if it updates risk models. Operators deploying analytics report measurable reductions in inspection downtime, largely because they can defer intrusive work on segments where monitoring data provides equivalent assurance.
The Economics Have Changed
From Project Spend to Subscription
Field inspection is labour-intensive and priced per campaign. Software and monitoring are priced per mile per year. The second model produces recurring revenue, higher margins, and far more predictable earnings — which is why vendors are pushing to convert inspection events into data subscriptions.
The Balance Sheet Channel
Insurers apply premium differentials between operators with verified continuous monitoring and those relying on calendar inspection. Lenders increasingly condition refinancing on documented integrity performance. Integrity spending has therefore become a balance-sheet lever rather than a pure cost centre, which accelerates budget approval.
Segment Dynamics Worth Understanding
Brownfield Dominance
Operational pipelines account for the large majority of industry revenue because the installed base dwarfs annual additions. Legacy material uncertainty forces conservative assumptions and higher-resolution tooling, which raises revenue per mile even where mileage is static.
New-Build Matters Disproportionately
New construction is a smaller revenue pool but a more consequential one, because design-stage decisions determine two decades of downstream service spend. Pre-installed fibre, higher steel grades, and piggability designed in at construction cost a fraction of retrofitting them later.
Offshore Premium
Offshore work carries revenue per mile several multiples above onshore. Deepwater consequence severity removes any incentive to defer, and autonomous underwater vehicles have expanded the addressable scope by reducing survey costs.
Restraints That Deserve Honesty
Workforce
Certified inspection personnel require years of supervised field experience to qualify. Contractor bid declines on remote campaigns occur purely for crew availability, and day rates have risen accordingly. This is a genuine constraint on growth, not a temporary shortage.
Legacy Records
Risk assessment requires validated material and construction records. Many older assets lack traceable mill certificates, and reconstructing verifiable operating limits requires destructive sampling or conservative de-rating. Fragmented records across acquired portfolios delay analytics deployment by a year or more on typical brownfield programmes.
Downtime Cost
Intrusive inspection on non-piggable segments requires flow reduction or interruption. Throughput loss on a major transmission line can be substantial per outage day, which encourages operators to defer to the latest compliant date and constrains the pace at which inspection volume can grow.
Opportunities Worth Watching
Hydrogen and CO₂ Repurposing
Converting existing methane lines to hydrogen or dense-phase CO₂ requires reassessment of fracture toughness, elastomer compatibility, and leak-detection thresholds. There is no established competitive incumbency in this assessment scope, which means firms that publish validated conversion procedures early can establish the de facto standard.
Outcome-Based Contracting
Contracts increasingly tie payment to regulatory outcomes — reduced leak rates, improved availability — rather than day rates. Operators will pay premiums when suppliers share performance risk. The data rights clauses in these contracts matter enormously and are frequently underspecified in legacy agreements.
The Long Tail of Small Operators
Expanded regulatory scope brought thousands of gathering-system and distribution operators into formal programmes, most of which lack any integrity software. Template-driven platforms priced per mile rather than per enterprise seat address a segment that has historically run on spreadsheets.
Future Direction
Two developments will define the next decade. Machine-learned anomaly classification is approaching human accuracy on routine corrosion features, which will compress interpretation time from weeks to days. And platform consolidation will continue as operators refuse to reconcile data across disconnected systems, pushing vendors to acquire point solutions and offer integrated suites.
Neither development eliminates the need for engineering judgement. What changes is where that judgement is applied — less on routine feature classification, more on complex features and on the engineering case that justifies interval extension.
Practical Conclusions
For operators, the priority is to establish a single trusted centreline and verified material records before investing in analytics. Without that foundation, risk scores are not defensible.
For vendors, the priority is to convert campaign revenue into subscription revenue without losing the field execution capability that makes the data credible.
For investors, the useful metric is revenue mix between recurring subscriptions and campaign work, because subscription-weighted providers show materially lower earnings volatility across commodity cycles.
Dive into related studies for a broader industry perspective:
Power Battery Management System Market
Solar PV Mounting Systems Market
Categorias
Leia mais
NEWARK, Del., October 8, 2026. — The global starch derivatives market is estimated at USD 99.5 billion in 2026 and is projected to reach USD 160.6 billion by 2036, expanding at a CAGR of 4.9% from 2026 to 2036, according to Future Market Insights (FMI). The market stood at USD 94.9 billion in 2025. The growth outlook is being shaped by rising production of processed food, beverages, paper...
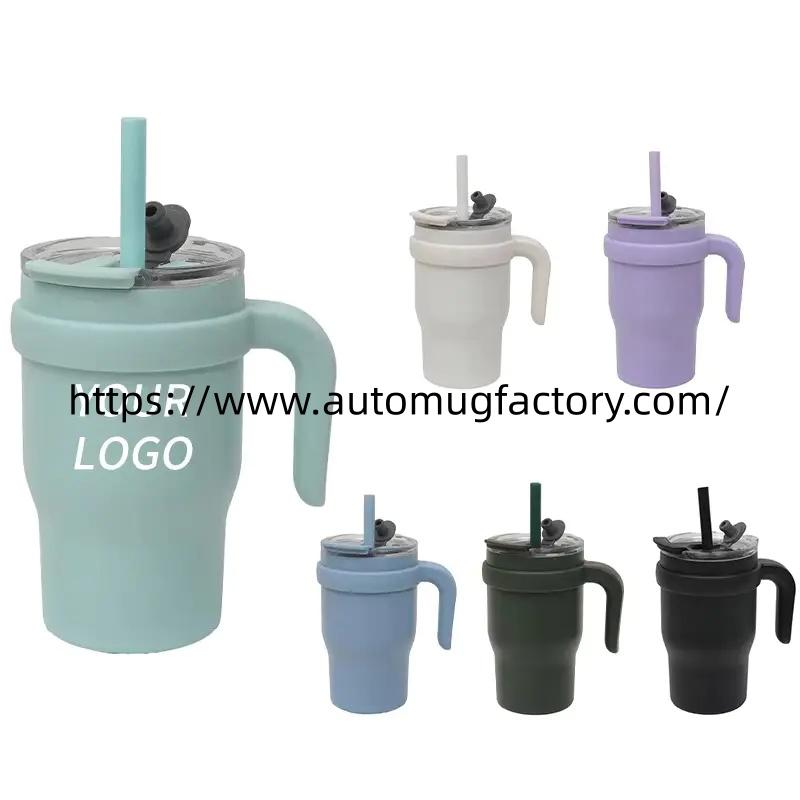
Coffee mugs often become part of familiar daily routines, yet their design involves decisions that extend beyond holding a beverage. For businesses evaluating a Coffee Mug Factory, understanding the relationship between materials, production methods, handling comfort, and visual presentation can help clarify which products suit a particular market. A successful mug needs to work naturally for...
The global space electronics market is experiencing significant growth, driven by the surge in satellite constellations, increasing deep space exploration missions, and the modernization of defense and communication infrastructure. Space electronics, also known as astrionics, are specialized components and systems engineered to withstand the extreme conditions of space, including radiation,...
Bilgisayar çağı, teknoloji insanlık tarihinin en hızlı değişim ve dönüşüm yaşadığı dönemlerden biridir. teknoloji Bu çağda bilgiye erişim, iletişim ve üretim süreçleri büyük ölçüde dijital ortamlar üzerinden gerçekleşmektedir. Türkçe de bu dönüşümden önemli...
The global effort to reduce atmospheric carbon dioxide concentrations and mitigate climate change is being advanced by carbon capture and sequestration technologies that capture emissions from industrial sources and store them permanently underground. According to Market Research Future, the Carbon Capture and Sequestration Market was estimated at USD 3.882 billion in 2024 and is projected...