Europe Syngas Market Analysis Reveals Emerging Opportunities in Waste-to-Energy Solutions
Competition in the European syngas industry involves technology developers, industrial gas suppliers, engineering companies, chemical producers, and energy businesses. Participants compete through process efficiency, project execution, equipment reliability, feedstock flexibility, and the ability to deliver gas suited to downstream industrial requirements. Because syngas production often requires substantial capital investment, technical expertise and long-term commercial relationships can be important competitive advantages.
Companies involved in industrial gas and chemical processing may pursue integrated projects that connect syngas production with hydrogen purification, chemical synthesis, or other downstream applications. This approach can create a more coordinated production chain and help align supply with customer demand. Engineering and technology providers may differentiate themselves through gasification design, reforming systems, process controls, gas cleaning, and emissions-management solutions.
Within the Europe syngas market, investment decisions are influenced by energy prices, environmental policies, customer demand, infrastructure availability, and the expected cost of producing syngas over the facility’s operating life. Developers must assess whether a project can secure sufficient feedstock, maintain reliable output, and compete with alternative sources of hydrogen and chemical intermediates.
Strategic partnerships can help distribute risk and combine complementary capabilities. A technology supplier may contribute process expertise, an industrial customer may provide a long-term offtake agreement, and an infrastructure operator may support gas transportation or carbon dioxide management. Such arrangements can improve project coordination, although each participant must carefully evaluate commercial obligations and technical responsibilities.
Innovation is also influencing competitive positioning. Companies investing in lower-emission production methods, improved conversion efficiency, and effective monitoring systems may be better equipped to meet customer expectations. However, environmental benefits must be supported by transparent performance data and realistic lifecycle assessments.
Market participants also face uncertainties related to project financing, permitting timelines, changing energy prices, and the pace of industrial investment. Large projects can take considerable time to plan and construct, making demand forecasting and risk management essential. Modular systems and phased development may provide flexibility for some applications, but their suitability depends on production scale and operating requirements.
In the long term, competitive success is likely to depend on more than production capacity alone. Companies that combine technical performance, dependable supply, effective cost control, strong customer relationships, and credible emissions strategies may be positioned to capture opportunities as European industry modernizes.
Categorias
Leia mais
When facilities require advanced air movement capabilities a Multi Stage Centrifugal Fan Manufacturer stands prepared to address complex ventilation challenges across multiple sectors. Operations encounter situations where pressure demands surpass simple setups so layered impellers come into play building force progressively. This approach allows streams to travel extended routes inside ducts...
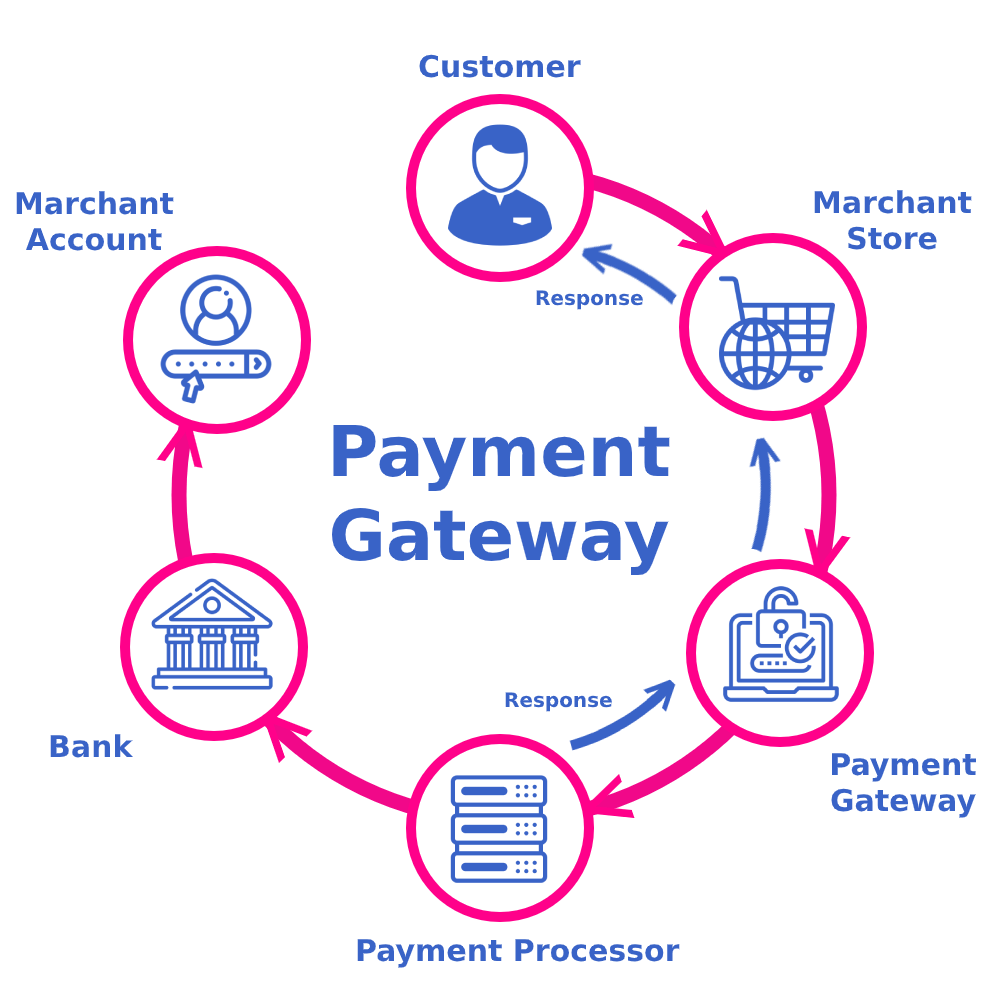
The rapid evolution of consumer payment preferences and retail technology is giving rise to distinct macro and micro trends across the global payment services sector. An in-depth evaluation of the Online Payment Gateway market trends highlights a clear movement toward payment orchestration platforms that allow merchants to connect to multiple gateways through a single software interface. This...
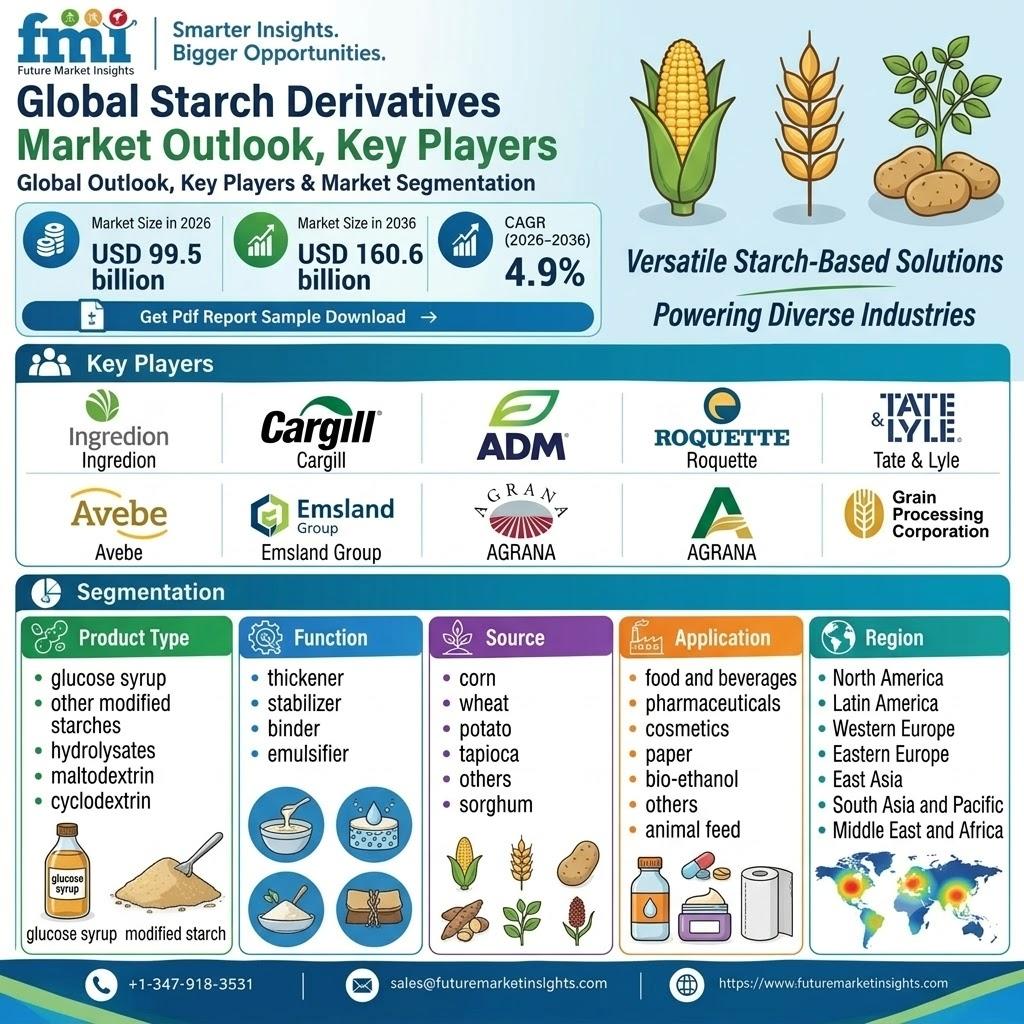
NEWARK, Del., October 8, 2026. — The global starch derivatives market is estimated at USD 99.5 billion in 2026 and is projected to reach USD 160.6 billion by 2036, expanding at a CAGR of 4.9% from 2026 to 2036, according to Future Market Insights (FMI). The market stood at USD 94.9 billion in 2025. The growth outlook is being shaped by rising production of processed food, beverages, paper...
Pneumatic Punching Machine is widely considered by factories that need practical solutions for metal forming and component production. In many manufacturing environments, companies look for equipment that can support repeated tasks, maintain stable operation, and fit different production arrangements. As industrial processes continue to develop, manufacturers are paying more attention to...
The Corporate Blended Learning Market is rapidly gaining traction as organizations seek more efficient, flexible, and scalable training solutions. Blended learning, which combines traditional classroom instruction with digital and online learning modules, has emerged as a powerful approach to enhance employee skills and productivity. In today’s competitive business environment, companies...